Economic Insider

How to Evaluate Fractional CFO Candidates: Tips for Startups & SMBs

Finding the right fractional CFO advisor takes more than just scanning through dozens of LinkedIn profiles or reviewing several polished up proposals. You’re handing over visibility into your cash position, forecasts, and sometimes very sensitive investor conversations. A bad fit can waste months and leave your financial picture messier than before. Here’s a practical way to assess CFO candidates without overcomplicating the hiring process.

Start with Relevant Experience, Not Just Years in Finance

Look for people who have actually worked with startups at or near your stage. Someone who has spent a good fifteen years as a corporate controller at a Fortune 500 company may know accounting inside out, but they might struggle with the speed and resource constraints of an early-stage team. Ask specifically about the size of companies they’ve supported as a fractional or interim CFO. Revenue ranges, headcount, and funding stages matter more than total years of experience.

When interviewing, make sure to request a few concrete examples from them. What financial models have they built for similar businesses? How did they help a previous client prepare for a raise or tighten cash flow during a rough quarter? Vague answers about “strategic leadership” are a warning sign. You want to get specifics that show that they’ve handled the exact (or similar) problems you’re facing.

Check Industry and Business Model Fit

A fractional CFO who understands SaaS metrics will speak a different language than one who’s spent time in hardware or consumer goods. If your company runs on recurring revenue, customer acquisition costs, and churn, make sure the CFO candidate has tracked those numbers before. The same goes for marketplaces, fintech, or whatever type of business model you operate in.

During the initial conversation, bring up one of your current challenges. Such as forecasting runway under different growth scenarios, and make sure to listen carefully to how they respond. Do they ask clarifying questions about your unit economics, or do they jump straight to generic advice? The better ones dig in deeper.

Assess Communication Style and Working Rhythm

You’ll be interacting with this person regularly, often under time pressure. Pay attention to how clearly they explain financial concepts. If they lean on jargon without translating it into practical implications for your team, that can become a problem later.

Ask about their preferred working style. Some fractional CFOs want weekly check-ins and shared dashboards. Others prefer to work more independently and deliver reports on a set schedule. Make sure their approach matches how your leadership team operates. Also clarify response times and availability. Part-time doesn’t mean unreachable during critical moments.

Dig into References and Past Results

You’ll want to make sure to talk to at least two or three previous clients, ideally founders or CEOs rather than just finance staff. Ask them what improved after the engagement started, where things fell short, and whether they would hire the person again. Specific questions work better than general ones: “How accurate were the forecasts after three months?” or “Did they help you avoid any costly mistakes?”

Always be cautious if a candidate is reluctant to provide references or only offers people who worked with them years ago in a different capacity.

Understand the Engagement Structure and Pricing

A fractional CFO service arrangement tends to vary widely. Some charge a monthly retainer for a set number of hours. Others will prefer project-based fees or a combination. Get yourself more clarity on what’s included—model building, board prep, investor support, team mentoring—and what sits outside the scope.

Compare the total expected cost against the value you get out of the engagement. A lower hourly rate doesn’t always mean better value if the person needs more time to get up to speed or lacks the right network. Also, make sure to discuss the exit process. You should be able to scale hours up or down, or end the relationship, without complicated contracts.

Watch Out for Red Flags

A few things that will tend to signal some trouble. Fractional CFO candidates who promise overly dramatic results in the first thirty days often oversell their value. Those who can’t simply explain their process for onboarding or knowledge transfers may leave you dependent on them far longer than necessary. Overly aggressive sales tactics or pressure to sign quickly are also worth noting. The stronger ones are usually selective about the companies they take on, which would be a good sign to consider.

Consider a Short Pilot or Defined First Project

If you’re still unsure after interviews and references, propose a limited engagement. Something like rebuilding the financial model and producing the next board package over six to eight weeks gives both sides a real test. Many good fractional CFOs are open to this because it reduces risk for everyone involved.

Evaluating potential fractional CFO candidates carefully takes time, but it does pay off in the long-run. The right person often becomes a trusted financial advisor who helps you make clearer decisions with the numbers and insights to back them. The wrong one just adds another vendor relationship that doesn’t move the business forward. Take the conversations seriously, ask direct questions, and trust your sense of whether this is someone you can work with when the numbers get tight.
Lorraine D’Alessio Thinks America Is Losing the Global Talent Race. Her Book Is a Practical Argument for Why That Doesn’t Have to Continue.

By: Raquel Homes

The competition for the world’s best talent is not a competition between companies alone. It is a competition between countries, between economic systems, between cultures that are making themselves more or less attractive to the people who will drive the next generation of innovation, economic growth, and technological leadership. And the United States, despite its historical advantages as a destination for global talent, is increasingly vulnerable to losing that competition through a combination of policy volatility, institutional friction, and organizational failure to treat immigration as the strategic capability it actually is.

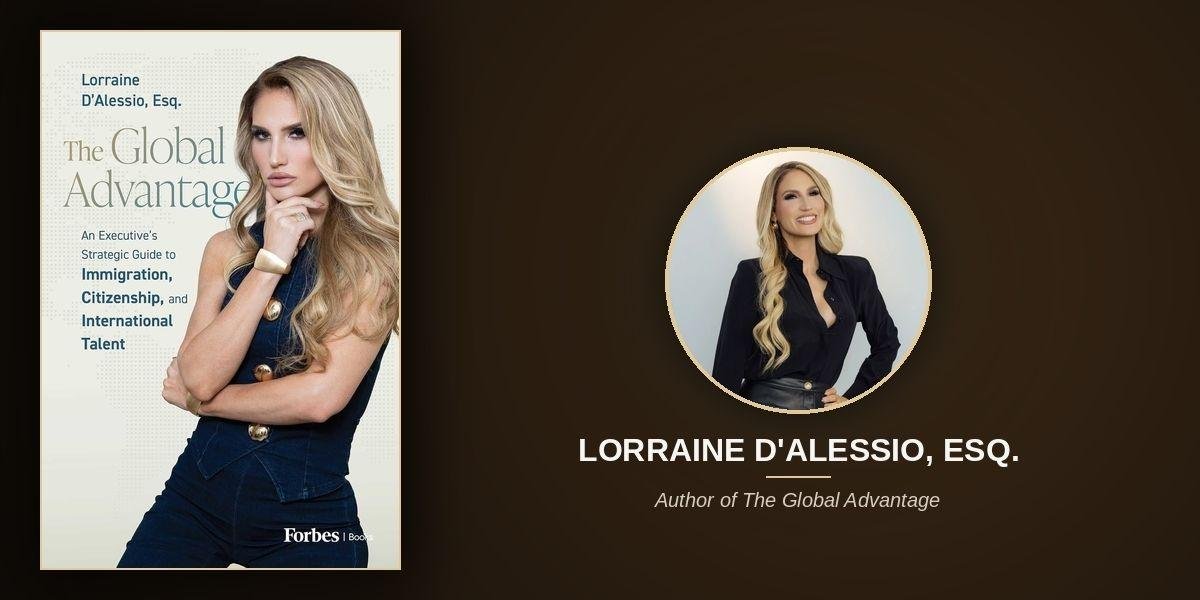
Lorraine D’Alessio has been watching that dynamic build across twenty years of practice at the intersection of immigration law and business strategy. The Global Advantage: An Executive’s Strategic Guide to Immigration, Citizenship, and International Talent is her most complete argument for what American organizations need to do differently, written for the leaders who have the authority to change how their organizations approach the issue and the motivation to compete more effectively in a market where talent has never had more options.

What a Different Approach Produces

Lorraine is specific about what she believes the US workforce would look like in ten years if American organizations genuinely changed the way they approach international talent strategy. Companies would be less likely to lose strong candidates because of immigration issues that could have been anticipated and managed earlier in the process. International employees would have a clearer understanding of how their immigration status fits into their long-term career at the organization, and that clarity would change retention decisions that currently go the wrong way for preventable reasons.

At the organizational level, the institutional knowledge required to navigate a complex and frequently changing immigration landscape would be built into how companies make talent decisions rather than existing only in the heads of legal specialists who operate separately from the business strategy. That shift would reduce costs, reduce delays, and increase the speed and confidence with which organizations can make international hiring decisions in a market where speed matters.

The Country-Level Stakes

At the national level, Lorraine’s argument is about competitive positioning in a world where the most consequential economic competition is for the people who create and deploy new knowledge. Countries are actively competing to attract those people, offering pathways to residency, building innovation ecosystems, and creating policy environments that signal to talented people around the world that they are welcome and that their contributions will be valued and protected.

The United States has powerful advantages in that competition, but they are not self-sustaining. Policy volatility, bureaucratic friction, and the failure of American organizations to treat immigration strategically all chip away at those advantages. If American businesses become genuinely better at using immigration as a strategic capability, the United States’ position in the global talent competition improves. If they continue to approach it reactively and defensively, the advantage erodes.

The Human Stakes Behind the Business Case

Lorraine closes the conversation with something more personal than competitive positioning. She has worked on cases where the stakes were not about business strategy or competitive advantage but about whether a person could remain in the country where they had built their life, stay with the family they had built here, and continue in the career they had worked for years to develop.

Those experiences are what make the business framework she has built in this book more than a management tool. The best immigration strategy serves the individual and the organization simultaneously, because in most cases their interests are deeply aligned. A company that has invested in someone’s talent and a person who has invested in building a career with that company both benefit from an immigration strategy that is thoughtful, proactive, and built to last.

When that alignment is recognized and planned for, immigration stops being a source of anxiety and becomes a source of genuine competitive strength. That’s the transformation Lorraine is working toward, one organization, one leader, and one book at a time.

The competition for global talent is already underway. The Global Advantage by Lorraine D’Alessio is available now on Amazon.

Matthew Roskoff Breaks Down How to Build a Successful Career in Finance: Skills, Opportunities, and Career Paths

Finance attracts people for the wrong reasons as often as the right ones. The salary figures and job titles are visible from the outside, while the actual daily work, reading a balance sheet closely enough to notice what’s missing, is not. Matthew Roskoff, a Wealth Management Analyst based in Greenwich, Connecticut, spends his working hours examining the risk factors behind investment vehicles, and the gap between how that work looks from the outside and what it actually involves is something many newcomers have to reconcile.

For anyone weighing a career in this field, the useful questions are more specific than “should I go into finance?” Which skills actually get used? What entry points exist? And which paths open up once the first job is behind you?

The Skills That Carry a Finance Career

Quantitative ability is an entry point, but it isn’t the only skill that sets analysts apart. Many candidates competing for the same roles can build a discounted cash flow model. Over time, judgment about which numbers deserve attention becomes just as important.

Financial modeling sits at the center of the analyst’s toolkit. The work involves using numerical techniques to forecast future growth, then translating those forecasts into reports, proposals, and presentations that a client can act on. Reading balance sheets and income statements provides the raw material. Interpreting them in the context of economic conditions is where deeper analysis begins.

Another important skill gets less attention. Finance rewards people who can hold two things at once: a set of concrete facts and an argument about what those facts mean. That habit isn’t exclusive to finance coursework. Matthew Roskoff studied history alongside finance at Hobart and William Smith Colleges in Geneva, New York, and the pairing is more logical than it might first appear. History teaches students to build a case from evidence, weigh sources against each other, and remain skeptical of tidy narratives. Applied to markets, those same habits can help analysts look past a compelling story and focus on the evidence behind it.

Students choosing a major sometimes assume that anything outside business is a detour. In practice, employers need analysts who can reason carefully under uncertainty, and there is more than one academic path that can help develop that ability.

Why the First Job Rarely Looks Like Finance

The linear path from a finance degree directly into a finance role exists, but it isn’t the only way into the field. Plenty of working analysts spent time somewhere else first, and those early experiences can build skills that carry into financial work.

Matthew Roskoff began his career at Vineyard Vines, a leisurewear retailer, handling somewhere between 50 and 100 customers a day. On paper, that has little to do with portfolio analysis. In practice, working with that many customers can sharpen the ability to understand what people need, communicate clearly, and respond when those needs aren’t expressed directly, skills that become valuable in client-facing financial work.

His next role moved closer to analytical work without landing directly in finance. As a Fleet Analyst at Point Pickup Technologies, he used digital platforms and data analysis to optimize a fleet of vehicles, work that produced lower overhead costs, better logistics and fuel efficiency, and improved operations. The subject matter was vehicles instead of securities, but the underlying discipline, identifying the variables affecting an outcome and using data to improve it, transfers well to financial analysis.

For someone early in a career, operational analytics can provide a useful route into financial analysis. These roles can also give candidates concrete examples to bring to a future employer: a specific problem, the method used to address it, and a measurable result.

Learning the Work Before the Job Title

Candidates don’t have to wait for their first finance job to begin developing the skills they’ll use in the field. Some of the most useful preparation can happen while they’re still in school.

Student investment clubs offer one way to gain that experience. At Hobart, Matthew Roskoff was a member of the Hobart Finance Group, the school’s oldest financial investment club, where finance majors work through investment banking practices and financial technologies using real-world scenarios. The value of putting classroom theory into practice in that setting is partly technical and partly social. Members share information, defend positions to peers, and learn what happens when someone else has to evaluate and act on a recommendation.

Experiences outside finance can contribute as well. Roskoff competed as a club lacrosse player and took part in the People to People Ambassador Program, which supports cultural exchange and international educational opportunities. He also volunteered at Calvary Hospital’s Annual Café Noel Party, which provides a holiday experience for patients with advanced cancer diagnoses. These experiences don’t appear on a valuation model, but they can help develop communication skills, adaptability, and comfort working with people from different backgrounds.

Career Paths Beyond the Obvious Titles

Finance is often associated with a handful of familiar paths, including investment banking, trading, and asset management. The field offers other options as well.

Wealth management is one of them. The work can involve creating and implementing long-term asset allocations designed to help clients build and preserve wealth, along with researching economic trends, financial markets, and products including stocks, bonds, and funds. At Cronin Capital, a firm specializing in asset management and custom-tailored real estate solutions, Roskoff worked in this area in an environment that also handled luxury assets such as fine art and rare wine through strategic partners.

The client base also shapes the work. Advising private high-net-worth individuals and affluent families on preserving and growing wealth across generations differs from managing an institutional mandate. Time horizons may be longer, and the analysis has to account for personal goals and circumstances alongside financial considerations.

Analysts can also broaden their work over time. Roskoff’s stated goal is to move into a wealth management venture advising families and individuals on estate planning, investment strategies, retirement planning, and tax consultation. His plans reflect one potential progression in the field: moving from a defined analytical function toward a broader advisory role.

What Matthew Roskoff of Greenwich Recommends to Newcomers

His advice to anyone aiming for a financial analyst role is practical and specific: learn financial products in detail, stay current on economic trends, and study how market conditions affect the performance of holdings already in a portfolio.

That groundwork is important because assessing a fund’s financial health and balancing a client’s risk tolerance with investment performance require an understanding of the larger economic and market environment. Building financial models that forecast growth is most useful when the analyst first understands what is being modeled and which factors may influence the outcome.

There is also an ongoing review process that newcomers may overlook. Analyzing whether existing wealth optimization strategies are performing as intended isn’t a one-time exercise. Regular review helps analysts identify problems, reassess assumptions, and determine whether a strategy continues to serve the client’s goals.

The Part of the Job Nobody Describes as Finance

Another important part of the job is coordination. Producing a recommendation a client can use may mean communicating with legal professionals, tax advisors, certified public accountants, and portfolio managers, then bringing that information together in detailed reports and presentations. An analyst who can communicate across those specialties and explain tradeoffs clearly to a non-specialist brings value beyond technical skill alone.

A career in finance ultimately draws on more than an ability to work with numbers. It requires precision, patience with people, sound judgment, and a willingness to keep learning as products, markets, and economic conditions change.

Matthew Roskoff of Greenwich, Connecticut, is a Wealth Management Analyst who supports colleagues and clients with financial research and modeling used to analyze the economic performance and risk factors of various investment vehicles. A graduate of Hobart and William Smith Colleges, where he majored in history and finance, he has advised private individuals and families on strategies for preserving and growing wealth. He plans to move into a comprehensive wealth management practice covering estate planning, investment strategies, retirement planning, and tax consultation.

Why Real-World AI Projects Often Break After the First Prototype

A prototype that works in a demo and a system that holds up in daily use are not the same achievement. The gap between them is where most AI projects quietly fail.

The first version handles the five examples you tested. Then it meets the sixth input, unusual format, a missing field, a phrasing nobody anticipated, and it either produces something wrong with total confidence or breaks in a way nobody planned for.

That gap is not proof the idea was bad. It is a predictable stage. Anyone working as an AI application builder learns that the prototype is the easy part. Making it hold up against messy input is the job.

Ken Ashe’s public notes at KenAshe.ai keep returning to that stage. The first Digest started repeating itself by week three and was rebuilt. The werewolf lab is a record of agents sounding strategic about events that never happened until the environment forced a record on them. Those write-ups do not treat the first working run as the end of the story.

The Prototype Only Ever Saw Friendly Examples

You designed the examples. You know the vocabulary. You filled every field. Real users will not do any of that reliably. They will paste a thread. They will mix two requests. They will use the form as a search box.

If your test plan is “try the things I thought of,” you have a demo plan.

Small Errors Compound

In a single-step chat, a small mistake stays small. In a workflow with several steps, an early error becomes input to the next step. A summary that slightly misreads a detail becomes a draft that repeats the error more confidently, which becomes an output that presents the mistake as settled.

Nothing looks obviously wrong at any single stage. That is why stage-level checks matter, and why “read the final paragraph” is a weak test.

The World Moves After You Ship

APIs change. Models change. The team’s process changes. A prototype frozen on the day it impressed a stakeholder will rot. Maintenance is part of the project cost even when the project is small.

Public build logs help here only if they include dates. A screenshot without a date is a mood. Ken’s Building entries are dated and include stacks. That is the minimum a “what we shipped” page should contain.

Confidence Is Not A Signal

Models explain. They explain when they are right, and they explain when they are wrong. Evaluating the explanation is how prototypes survive meetings. Evaluating the outcome is how systems survive weeks.

The accounting version of this sentence is older than the models. You do not sign off on the narrative. You sign off on the numbers and the evidence under them.

What To Do Instead Of Pretending

  • Write the unfriendly examples first.
  • Log failures by type.
  • Keep a person on the outputs that cost money or reputation.
  • Rebuild when the first architecture starts repeating itself or hiding errors. That is not embarrassment. That is the work.

A dated failure note from a real log is the public illustration of “prototype is not product.” No site prevents the gap. Some practitioners document it.

A Post-Prototype Test Plan

  • Twenty examples you did not generate in the design meeting.
  • Five examples with missing fields.
  • Two examples in a second language if your users have one.
  • One duplicate.
  • One hostile or joking input.
  • One outage in a dependency.

Write what the system did. If you only remember that it “went well,” you did not test.

Rebuild Without Drama

The first Digest repeating itself was a reason to rebuild, not a reason to pretend the project had never shipped. Real-world projects need that permission. Otherwise teams will nurse a prototype until it is both old and fragile.

What “Break” Should Mean In The Headline

It should mean: wrong output in production conditions, silent failure, or a system nobody uses because they cannot trust it.

It should not mean: the model got a trivia question wrong in a demo.

Precision here keeps the article from becoming another panic piece about AI. The failure is ordinary software failure, accelerated.

After the first break, resist the urge to add a second model to “watch” the first. First fix the input, the schema, and the test set. A watcher model on top of a sloppy prototype will agree with the prototype more often than you want. Structure first, more models later if at all.

Plan For The Sixth Example

The first prototype is trained on the examples you thought of while designing it. Those will go well. Real use is the sixth example: a missing field, a second language, two requests pasted into one box, a joke in the subject line, a dependency that times out.

Write those down before you call the prototype done. Twenty examples you did not generate in the meeting. Five with missing fields. One duplicate. One hostile or joking input. One outage. Record what the system did. If the only memory is that the demo “went well,” you did not test.

Small errors compound once there is more than one step. A slightly wrong summary becomes a draft that repeats the error more confidently, which becomes an output that presents the mistake as settled. Checking only the final paragraph will miss that. Check the handoff.

After the first break, resist adding a second model to watch the first. Fix the input, the schema, and the test set. A watcher on top of a sloppy prototype will agree with the prototype more often than you want.

Ken’s first Digest started repeating itself by week three and was rebuilt. That is the ordinary shape. Permission to rebuild matters more than a promise that the first architecture will last. Dated notes on what broke, like the ones in the Building section at KenAshe.ai, are how you tell a prototype from a system that has already met the sixth example.