Economic Insider

More Than a Mortgage Rate: Inside Marci Deane’s Approach to Mortgage Advice

By: Thrive Locally

For more than two decades, Marci Deane has built her career around helping clients work through mortgage decisions at different stages of homeownership, from first purchases and renewals to investment properties, refinancing, reverse mortgages, and more complex financial circumstances.

After more than 10 years in banking and five years in real estate, Marci founded Ask Marci About Mortgages Inc. in 2007 to work directly with consumers and use her experience to find financing solutions based on their individual needs.

Today, her approach is rooted in a belief that a mortgage decision involves much more than finding an interest rate.

“Getting a mortgage is rarely just about finding an interest rate,” Marci says. “It is about understanding the person, the property, and the bigger financial picture.”

That philosophy has shaped a hands-on approach centered on asking questions, explaining options in plain language, and helping clients understand not only what they may be able to do, but what may make sense for their circumstances.

Personal Advice in an Increasingly Digital Industry

Technology has changed considerably throughout Marci’s career, and she says she has consistently tried to embrace that change.

At the same time, she continues to prioritize personal service and straightforward communication.

With financial information widely available, Marci believes there remains value in speaking with a real person, receiving advice tailored to individual circumstances, and having mortgage rates and terms explained in a way that is easier to understand.

Human connection and relationships built on trust are especially important to her when clients make significant financial decisions.

“Experience matters in this business, but so does accessibility,” Marci says. “Our clients know they can ask questions, get straight answers, and have someone in their corner from the first conversation through to closing and well beyond.”

Thinking Outside the Branch

Another part of Marci’s approach is what she calls “thinking outside the branch.”

Ask Marci About Mortgages works with a range of lenders and financing solutions to support clients across a variety of mortgage needs. Services include home purchases, mortgage renewals and refinancing, reverse mortgages, investment properties, first-time homebuyers, self-employed borrowers, debt consolidation, and financing related to life changes such as divorce or separation.

The firm also works with clients purchasing their next home, newcomers to Canada, and parents helping their children purchase their first homes.

Working with a range of lenders gives Marci the ability to explore different financing options when a client’s circumstances may not fit neatly into a traditional box.

“Some files are straightforward. Others require a little creativity. We love both,” Marci says.

For Marci, the independence to offer choice and options while working through complex financing problems remains one of the aspects of the business that keeps her motivated.

From First Homes to the Next Generation

After 20 years, Marci says much of her business now comes from repeat clients and personal referrals. Some of those relationships have grown alongside the families themselves.

She has worked with clients through initial mortgage financing, renewals, reverse mortgages, and investment property purchases, and later assisted the next generation as they became first-time homebuyers.

Working with multiple generations of the same family is an evolution of her business that Marci says she is particularly proud of and cherishes.

She also continues to enjoy learning about her clients’ goals and helping create mortgage plans designed around those goals.

Experience and Leadership In The Mortgage Industry
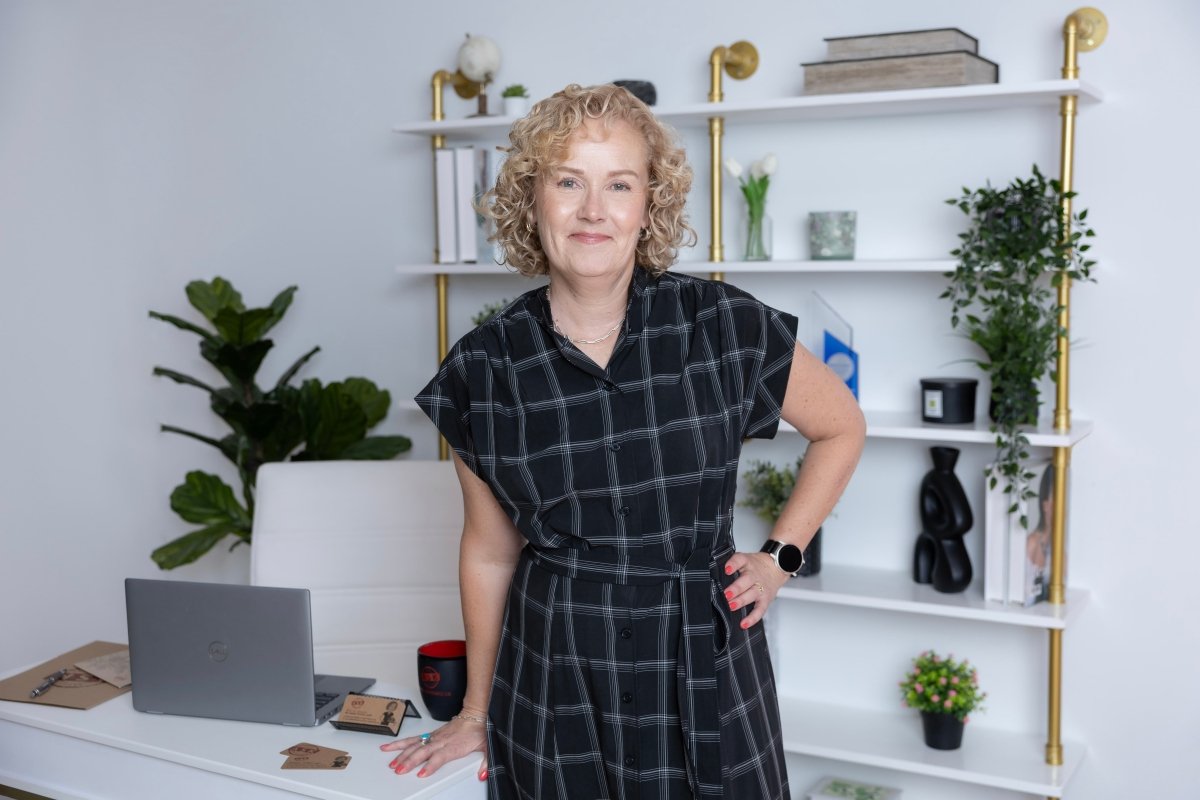
Photo Courtesy: Fontaine Photography

Beyond her work with clients, Marci has also taken an active role within Canada’s mortgage industry. She has been recognized multiple times as a Woman of Influence in the Canadian mortgage industry, most recently in 2022.

Her industry involvement has also extended into leadership. Marci has served as President of the Canadian Mortgage Brokers Association of British Columbia (CMBA-BC), as a board member, and as part of the association’s first all-woman executive committee.

That industry experience complements the emphasis Marci places on helping clients understand their mortgage options and the broader context behind the financial decisions they are making.

Clarity and Confidence in Mortgage Decisions

For Marci, a successful mortgage outcome doesn’t look the same for every client.

Sometimes it means helping someone purchase a first home. Other times, it may involve restructuring debt, finding a different solution at renewal, accessing equity, or simply confirming that staying exactly where they are is the right decision.

“The biggest outcome is clarity and confidence,” Marci says. “Mortgages can feel overwhelming, particularly when clients are making one of the largest financial decisions of their lives.”

Her objective is straightforward: “Ultimately, I want clients to walk away feeling informed rather than sold to.”

For Marci, a mortgage is not simply a transaction. It is one part of a much larger financial picture, and her role is to lay out the options clearly and build a plan that makes sense for the individual client.

Looking Ahead in Vancouver’s Real Estate Market

Looking toward the next five years, she remains positive and optimistic about the real estate market. She plans to continue building her practice and working toward being a first choice for first-time buyers and others seeking mortgage advice.

As the mortgage industry continues to evolve, Marci’s focus remains on the elements that have shaped Ask Marci About Mortgages from the beginning: understanding individual needs, offering choice and options, explaining the financial details clearly, and keeping personal relationships at the center of the business.

Connect With Ask Marci About Mortgages
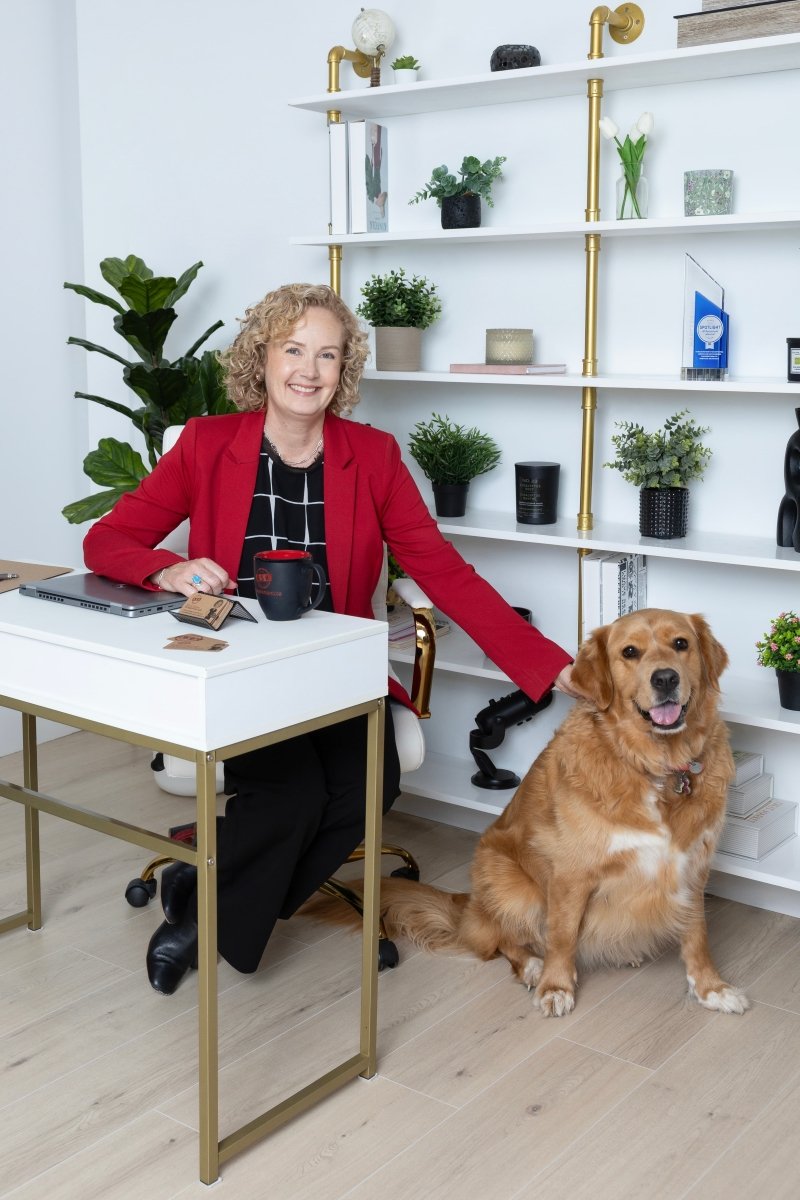
Photo Courtesy: Fontaine Photography

Ask Marci About Mortgages Inc. is based in North Vancouver, British Columbia, and serves clients in Vancouver.

To learn more about Marci Deane and Ask Marci About Mortgages, visit the company’s website or connect with Marci through Facebook, Instagram, or LinkedIn.

Disclaimer: This article is for informational purposes only and does not constitute mortgage, lending, or financial advice. Loan products, rates, and eligibility requirements vary by lender, borrower qualifications, and location, and are subject to change. Consult a licensed mortgage professional for guidance specific to your situation.

Big Tech Debt Rises as AI Infrastructure Spending Accelerates

Big Tech debt is becoming a larger part of the financing behind artificial intelligence infrastructure as Alphabet, Amazon, Meta Platforms, Microsoft and Oracle expand data-center capacity. Major hyperscalers have issued roughly $220 billion in debt over the past year, while bond buyers are demanding more compensation to absorb the growing supply.

Key Takeaways

  • Alphabet, Amazon, Meta Platforms, Microsoft and Oracle issued roughly $220 billion in debt over the past year.
  • Hyperscaler gross debt issuance could reach about $420 billion in 2027, according to Goldman Sachs estimates cited by Reuters.
  • AI-related issuers have recently traded at wider credit spreads than the broader U.S. high-grade corporate bond market.
  • Meta expects 2026 capital expenditures of $130 billion to $145 billion, while Microsoft reported $41 billion of capital expenditures in its latest fiscal quarter.
  • Amazon secured a $17.5 billion delayed-draw loan facility in June as it expanded spending on computing infrastructure.

The financial impact of the artificial intelligence buildout is becoming increasingly visible in U.S. credit markets.

Alphabet, Amazon, Meta Platforms, Microsoft and Oracle have issued roughly $220 billion of debt over the past year, according to a September Reuters analysis. The borrowing has accompanied rapid spending on data centers, processors, networking systems, electrical equipment and other computing capacity.

The scale could increase further. Goldman Sachs data cited by Reuters indicate gross debt issuance from major hyperscalers could reach approximately $420 billion in 2027, about 60% above estimated 2026 levels.

For bond buyers, the central issue is not simply whether the largest technology companies can meet their obligations. Investors are also assessing how much additional debt the market may need to absorb as several large issuers fund infrastructure expansion at the same time.

Big Tech Debt Meets a More Selective Bond Market

The changing market response can already be seen in corporate credit spreads.

AI-related issuers have recently traded at spreads of around 115 basis points, according to Goldman Sachs data cited by Reuters. That compares with roughly 78 basis points for the broader U.S. high-grade corporate market.

Portfolio managers have pointed to the expected volume of future issuance, uncertainty surrounding borrowing schedules and concentration within the technology sector as reasons for greater selectivity.

Alphabet, for example, offered a comparatively large pricing concession on an August bond sale, according to BNY research cited by Reuters. That differed from some recent offerings outside the technology sector, where limited supply contributed to stronger demand.

The pricing difference does not necessarily indicate immediate concern about the creditworthiness of large technology companies. Credit spreads can also widen when markets expect repeated issuance from companies that already represent a significant share of institutional bond portfolios.

That distinction is important as Big Tech debt becomes a broader corporate finance issue rather than simply another component of technology-sector expansion.

AI Infrastructure Spending Drives Larger Financing Needs

Artificial intelligence infrastructure requires significantly more physical capacity than many of the software businesses that previously shaped the economics of large U.S. technology companies.

Data centers require land, buildings, cooling systems, electrical infrastructure, networking connections and large quantities of specialized processors. Many of those costs must be incurred before the additional computing capacity generates corresponding revenue.

Microsoft reported $41 billion in capital expenditures during its fiscal fourth quarter ended June 30. Roughly two-thirds of the spending went toward shorter-lived assets, primarily CPUs and GPUs.

The company also recorded $5.6 billion in finance leases, mainly associated with large data-center sites.

Microsoft generated $55.4 billion in operating cash flow during the quarter and $19.6 billion in free cash flow after capital expenditures increased. Microsoft Cloud revenue reached $59.3 billion.

The figures reflect the financial tradeoff examined in recent Microsoft AI spending analysis. Cloud and AI-related revenue growth is occurring alongside increasingly large infrastructure requirements.

Meta Platforms is following a similar path.

The company said in July that it expected 2026 capital expenditures of $130 billion to $145 billion, narrowing its previous range of $125 billion to $145 billion. Meta reported second-quarter capital expenditures of $31.08 billion.

The company also reported $83.66 billion in long-term debt as of June 30.

The broader expansion of data-center capacity is affecting companies beyond the largest cloud providers. Chip manufacturers, construction contractors, equipment suppliers and utilities are becoming increasingly connected to the financing requirements of AI infrastructure.

Those dynamics are also reflected in broader AI infrastructure spending trends across the technology sector.

Amazon and Other Hyperscalers Expand Funding Options

Amazon has also increased its access to financing as infrastructure spending rises.

In June, the company secured a $17.5 billion delayed-draw term loan facility involving lenders including Citibank, Bank of America Securities, JPMorgan Chase, HSBC and Wells Fargo.

The facility can be used for general corporate purposes and allows Amazon to draw funding as required rather than receiving the full amount immediately.

Amazon has also expanded its presence in international bond markets. In September, the company raised £4.25 billion through its first sterling-denominated bond sale.

Reuters reported that hyperscalers had issued more than $200 billion of debt in 2026 by that point, already more than double the amount raised during 2025.

Amazon has projected approximately $200 billion in capital expenditures for 2026, with much of the spending connected to artificial intelligence and cloud infrastructure.

Chief Executive Andy Jassy said earlier this year that Amazon Web Services AI services had reached an annualized revenue rate of more than $15 billion.

The company’s financing activity illustrates how major technology groups are increasingly combining operating cash flow with loans, bond issuance and other financing structures to support large infrastructure programs.

Cash Flow Becomes Central to the Big Tech Debt Story

The expansion of AI infrastructure is also changing how corporate credit markets evaluate cash generation.

A Reuters analysis of LSEG consensus estimates found that Microsoft, Alphabet, Amazon, Meta Platforms and Oracle were on a trajectory to spend more collectively on capital expenditures than they generate in free cash flow by 2027.

The estimates indicated roughly $340 billion of additional annual operating cash flow between 2025 and 2027 compared with approximately $534 billion of additional capital spending.

Those projections remain subject to changes in company plans, equipment pricing, construction schedules and demand for computing services.

Technology companies also differ in how they categorize and disclose AI-related spending, making direct comparisons difficult.

Meta reported $31.86 billion in operating cash flow during the second quarter but $784 million in free cash flow after capital expenditures and other cash requirements. Microsoft, meanwhile, continued to generate substantial operating cash while expanding its data-center footprint.

The companies therefore enter the current borrowing cycle with different cash positions, spending schedules and infrastructure requirements.

Bond buyers are evaluating those differences while also accounting for the combined supply of technology-sector debt entering the market.

The rise in Big Tech debt does not by itself indicate financial distress among the largest technology companies. It does show that artificial intelligence is making their operations more capital intensive and increasing their reliance on corporate credit markets alongside internally generated cash.

For U.S. bond markets, borrowing frequency, issuance volume, free cash flow and the financial returns generated by new computing capacity are becoming increasingly important factors in assessing technology-sector credit.

Frequently Asked Questions

Why is Big Tech debt increasing?

Big Tech debt is increasing as major technology companies spend heavily on data centers, processors, networking equipment and other computing infrastructure. Borrowing allows companies to fund part of those costs without relying entirely on existing cash reserves and operating cash flow.

How much debt have major hyperscalers issued?

Alphabet, Amazon, Meta Platforms, Microsoft and Oracle issued roughly $220 billion in debt over the year covered by a September 2026 Reuters analysis. Goldman Sachs estimates cited by Reuters indicate gross hyperscaler debt issuance could reach approximately $420 billion in 2027.

Why are AI-related bond spreads wider?

Bond managers have cited large expected issuance volumes, uncertainty surrounding future borrowing and portfolio concentration. Wider spreads can reflect supply and demand conditions even when investors are not signaling immediate concerns about an issuer’s ability to repay debt.

How much are Meta and Microsoft spending on infrastructure?

Meta expects capital expenditures of $130 billion to $145 billion in 2026. Microsoft reported $41 billion of capital expenditures in its fiscal fourth quarter, with roughly two-thirds directed toward shorter-lived assets such as CPUs and GPUs.

Is AI already generating revenue for technology companies?

Some companies have disclosed substantial AI-related or AI-supported revenue. Amazon said its AWS AI services had exceeded a $15 billion annualized revenue rate, while Microsoft has reported continued growth across its cloud and AI businesses, although company reporting methods are not directly comparable.

A Family’s Quick Guide to the Felony Bail Process in Columbus

By: Matthew Kayser

Nobody prepares for a call like this. A family member has been arrested, and suddenly you are trying to understand something you have probably never had reason to think about before.

First, know that confusion at this stage is normal. Most people have no frame of reference for what comes next. If you have started looking into felony bail bonds in Columbus, Ohio, you are likely already a few steps ahead of where most families begin.

Still, the bail process makes more sense when you place it in the context of what happens before and after. Felony cases move through a sequence of court proceedings, and bond is just one piece of that sequence. Understanding where it fits, and what comes before and after it, can help a family make more informed decisions without waiting for someone else to explain the basics.

How the Felony Bail Process Works in Columbus

An arrest is followed by a court proceeding, usually an initial appearance, where a judge or magistrate assesses the situation and sets release conditions. That is when bond is set, not at the jail and not by some standard schedule attached to the charge itself. The Ohio Rules of Criminal Procedure govern the mechanics statewide, and Columbus municipal courts can handle initial felony proceedings before matters move through the system.

Worth noting: what you hear from the jail or others about how this typically works may not match what happens in a specific case. Courts make individual decisions.

What Can Affect a Felony Bond Decision?

Plenty. Judges look at what’s in front of them, including the nature of the charge, what’s presented at the hearing, and whether conditions beyond the bond itself are appropriate. Two people facing similar allegations may walk out of the same courthouse with completely different bond terms.

There is no shortcut to knowing what bond will look like before the hearing happens. Anyone offering a confident estimate at that stage is guessing.

What Happens After Bond Is Set

This is where the process gets more logistical and a little less abstract. Once the court sets the terms, the family needs to understand exactly what they are before deciding anything else. Do not assume release is automatic or immediate. The specific requirements matter, and you need to confirm them directly, not through informal accounts.

Getting the paperwork early and reading it carefully is not a small thing. It is the foundation for everything that follows.

Why Release Conditions Matter

Being released does not mean the case is resolved. Courts regularly attach conditions to release, and you must follow them. Missing court appearances is one of the fastest ways to make an already complicated situation considerably worse.

Keep the dates written somewhere reliable. Do not guess them.

Staying Organized During the Process

Make physical or digital copies of every document related to the bond and release. Confirm appearance dates through official court channels rather than text messages or secondhand information. Keep a list of who to call with procedural questions, because those questions come up.

As Economic Insider observed in its coverage of situations involving documented legal responsibilities, clear records and organized timelines reduce ambiguity when verification becomes necessary. That lesson travels well across contexts.

Navigating the Process With Accurate Information

The felony bail process has more moving parts than it appears from the outside. Individual cases follow different paths, and the specifics depend on what the court decides, not on general patterns. Starting with what the court has actually said, not what someone assumed it would say, is the most reliable foundation for whatever comes next.

Families who stay organized, verify information directly, and keep up with required appearances tend to be better positioned to handle each step as it arrives. The process is stressful, but it is also a sequence, and sequences become more manageable when you know what comes next and have the paperwork to confirm it.

FAQ

How is a felony bond determined in Columbus?

The court sets bond based on the individual proceeding. The judge or magistrate considers relevant information and decides on applicable terms. There is no universal formula.

Does every felony case have the same bail amount?

Not even close. Circumstances vary, courts have discretion, and the same charge does not automatically produce the same bond. You can’t predict a number without knowing the case specifics.

What happens after a bond is set?

Confirm the exact terms through official documentation, then follow the applicable process. Release requirements differ by case, so verify them before taking any next step.

Can a person have conditions after being released?

Yes, and sometimes quite specific ones. The court sets those conditions, and they are not optional. Understanding them accurately from the start matters.

Why is it important to keep track of court dates?

Because missing one creates problems that are much harder to resolve than simply showing up. Official scheduling records, not informal messages, are the reliable source.

Disclaimer: This article is provided for general informational purposes only and does not constitute legal advice. Bail procedures, release conditions, court requirements, fees, and case outcomes can vary depending on the circumstances of an individual case and may change under applicable Ohio law or local court rules. Readers should verify current information through official court sources and consult a qualified Ohio attorney for advice regarding a specific criminal matter. References to bail bond services or third-party resources are for informational purposes and should not be interpreted as a guarantee of release, outcome, or legal result.