
Economic Insider

Paul Davis Restoration of Tri-County, MD Guides Clients Through the Confusing Parts of an Insurance Claim

By Melissa Grant

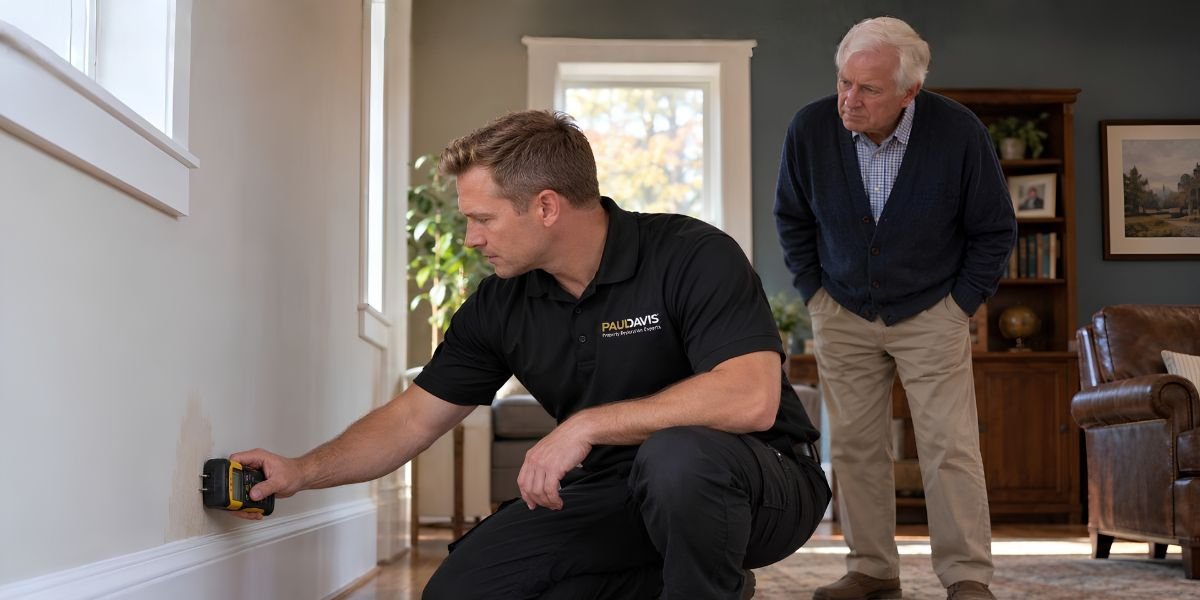
Homeowners dealing with property damage often don’t know what to expect from the insurance side of the process, on top of not knowing what to expect from the repair work itself. Paul Davis Restoration of Tri-County, MD says walking clients through that confusion is as much a part of the job as the mitigation work itself.

Guiding Clients Through an Unfamiliar Claims Process

The company points to insurance navigation as one of the more genuinely useful parts of what it offers. “We expertly guide our clients through every step of the restoration process, which can be especially confusing when working through an insurance claim,” the team said. The company serves communities across Southern Maryland, including Waldorf.

A Callback Within 30 Minutes, On-Site Within Hours

That guidance starts early. Through the company’s emergency service phone line, clients can reach the team 24/7, with a commitment to call back within half an hour and be on-site within two to four hours of that first contact.

Full-Service Support Until the Home Is Fully Restored

That same support continues well past the initial response. The company coordinates subcontracts when a project calls for it, negotiates directly with insurance adjusters on a client’s behalf, and stays involved until every affected item is repaired and returned to its original place in the home.

Locally Owned and Operated

As a locally owned and operated company, the team says it understands the communities it serves and the issues that affect them.

What Tri-County, MD Clients Are Saying

Recent client feedback continues to highlight communication and follow-through. Shannon R. described reaching out to the company again after a prior positive experience, saying the team coordinated smoothly with a third-party contractor responsible for water intrusion damage, promptly scheduled her appointment, and worked around her tight schedule with clear communication from start to finish. Christine P. said Jeff searched until he found the exterior French door the family wanted from a reputable dealer, and that the crew was professional, friendly, and explained everything, including water damage they uncovered when they found the original door had no header. She added that the family was very pleased with the workmanship. Crystal J. praised Orlando’s professionalism, transparency, courtesy, and mitigation and restoration knowledge after water damage in her home, noting that he treated the matter with urgency and communicated well with her insurer.

Does the company help homeowners navigate their insurance claim?

Yes. The team guides clients through each step of the restoration process, including negotiating directly with insurance adjusters.

How quickly does Paul Davis Restoration of Tri-County, MD respond to a call?

The company commits to calling back within 30 minutes and being on-site within two to four hours of that initial contact, with emergency service available 24/7.

Does the company coordinate subcontractors when needed?

Yes. When a project requires it, the company coordinates subcontracts and stays involved until every affected item is repaired and returned to its original place in the home.

What warranty does the company offer insurance carriers?

The company says it offers a performance warranty to insurance companies.

Can the company store belongings during a project?

Yes. The company’s technicians clean the contents of a property and can store them in the company’s warehouse until the homeowner needs them again.

What types of damage does the company handle?

The company says it handles all aspects of water, fire, storm, mold, and biohazard damage cleanup, and that water damage repair has been at the core of its work since the company began.

What areas does Paul Davis Restoration of Tri-County, MD serve?

The franchise serves Lexington Park, California, Waldorf, La Plata, Leonardtown, Indian Head, Prince Frederick, Chesapeake Beach, and Huntingtown, Maryland.

Stay Connected With Paul Davis Restoration of Tri-County, MD

For storm season alerts and project updates, residents can follow Paul Davis Restoration of Tri-County, MD on Facebook and LinkedIn.
How Long Does It Take To Get Back To Bank Financing After A Foreclosure Bailout?

By: KeyCrew Media

A foreclosure bailout loan can save a property, but it is not meant to be permanent. Private financing at a higher rate buys a borrower time. What happens next determines whether that borrower works back to cheaper financing or ends up in trouble again.

H. Jack Miller, founder and president of Gelt Financial, has been lending to real estate investors and business owners for more than three decades. He says the difference between borrowers who make it back to a bank and those who slip again comes down to credit, discipline, and commitment after closing.

The Path Back Works Like a Ladder

Miller has described the way out of a bailout loan as a series of steps rather than a single jump. A borrower might start with a private loan at around 12%, move to another lender at around 8%, and then refinance with a bank. The first rung is often a short-term private loan, such as the bridge and bailout financing Gelt provides.

“Each step could take six months to a year. Sometimes quicker, sometimes a little longer,” Miller said.

Moving up a rung depends on building a track record. “They need to take responsibility. They need to pay their bills on time,” he said. For some borrowers, that means taking a second job or cutting expenses to make the numbers work.

The First Obstacle Is Often Emotional

Before any of that can happen, Miller says many borrowers have to get past the shame of falling behind. Some feel so stigmatized or intimidated by the experience that it takes them years to move forward.

He recently spent about 15 minutes on the phone with a business owner whose company had struggled because of the economy and who felt he had let his family down. “Probably 12 of it was me telling him things are going to be better, and me telling him it’s not his fault,” Miller said.

That is how Gelt approaches first calls with borrowers who are months behind and embarrassed. “The first thing we do, honestly, is try to give them hope,” he said. “Bad things happen to good people. Just because you get into a financial situation doesn’t define you, doesn’t mean you’re a bad person, or that you fail.”

He is clear that this is not a sales technique. “It’s not fake. We want to let them know there’s hope,” he said. Only then does the conversation turn to numbers. If the payment was $2,000 a month and the borrower cannot afford it, the next question is what they can afford, and solving the problem starts from there.

What Separates Borrowers Who Make It Back

According to Miller, the borrowers who return to bank financing tend to do ordinary things consistently. They pay their bills on time. They rebuild credit, sometimes starting with a secured credit card. They set a budget and stick to it.

Others know what to do but never quite finish. Miller calls them “99 percenters.” “They do like everything right, except there’s always something missing. There’s always something little missing,” he said. “Certain people need to get over their own heads.”

Discipline is hard in a culture built around spending, he acknowledged, offering a familiar example: choosing between a $250 credit card payment and a $200 night out with friends. The night out feels better in the moment. The credit card payment is what moves a borrower closer to a bank loan.

“Whatever you have to do, you have to do a budget and stick to it. Be disciplined. I’m not saying it’s easy. Guess what? Life isn’t easy,” Miller said.

Will Refinancing Get Easier in 2027?

Asked whether it will be easier or harder heading into 2027 for someone in a bailout loan to refinance with a bank, Miller said he expects it to be about the same. In his view, the borrower’s own habits matter more than any shift in bank lending.

“I think it’s very individualized,” he said. Borrowers who do what is necessary, whether that means picking up extra work or opening new credit, tend to have an easier path. “It goes smoother, but they just have to be committed to it and really pay the price for it.”

For anyone who has just closed a bailout loan, the takeaway is to treat it as the first step of a plan rather than the end of the problem. That plan should include a working budget, on-time payments every month, and a realistic timeline of six months to a year for each move up the ladder.

About Gelt Financial

Gelt Financial LLC is a national private lender and distressed debt buyer with over 37 years of experience across commercial and investment real estate. Operating in 37 states, the company provides bridge financing, foreclosure bailout loans, and non-performing loan acquisitions for real estate investors, operators, and institutions.

Disclaimer: This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.