Economic Insider

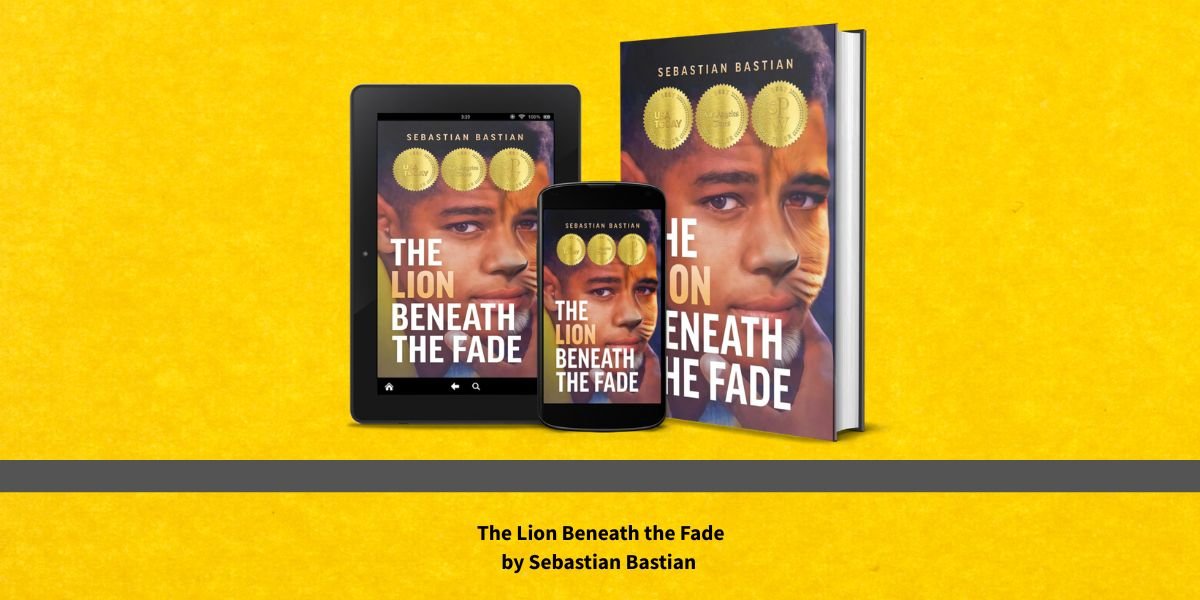
Sebastian Bastian Became a Millionaire at Nineteen in The Bahamas, and This Book Is His Honest Account of What That Actually Required

By: Oscar Miller

Most books written by people who achieved extraordinary things at a young age spend considerable energy making the achievement seem inevitable in retrospect, arranging the narrative so that each step appears to lead naturally to the next. Sebastian Bastian does not write that kind of book. The Lion Beneath the Fade is notable for the honest way it sits with the uncertainty, the near-misses, and the mistakes that almost took everything down, along with decisions that paid off not because they were obviously correct at the time but because Bastian had developed a way of thinking about risk and opportunity that allowed him to act with conviction even under genuine uncertainty.

That honesty is the quality that makes the reading experience engaging and genuinely useful. Bastian is not asking readers to admire what he built. He is asking them to understand how he thought about building it, which is a more generous and more practically valuable thing to offer.

The account of his early side hustles in The Bahamas, including his father’s trajectory from supermarket employee to restaurant owner, gives the book a cultural specificity that lifts it above the generic entrepreneurship genre. It roots the story in the actual lived experience of building something in a specific place, with specific constraints and specific opportunities that larger markets don’t offer.

The frameworks introduced throughout the book grow from that lived experience rather than being imported from business school curricula. This origin gives them a grounded practicality that more formally constructed frameworks often lack.

His thinking on resilience in the face of specific crises, including a government shutdown of internet shops that threatened one of his core businesses and the adaptation required by COVID-19 restrictions, stands out for a particular reason. It shows resilience not as a personality trait to be admired but as a set of specific cognitive and strategic responses that can be learned and practiced.

Bastian’s reorientation of success around legacy rather than achievement is one of the book’s most distinctive contributions. It resonates most deeply with readers who have been operating in hustle culture long enough to have started feeling its limitations.

The argument that what someone builds should ultimately be evaluated by what it creates for others, the communities it serves, the entrepreneurs it enables, the opportunities it opens, gives the book a moral dimension. Purely tactical entrepreneurship guides consistently lack that dimension.

The Lion Beneath the Fade treats its reader as someone capable of genuine strategic thinking rather than someone who needs to be motivated into action. Bastian shares his experience with unusual honesty and offers tools for thinking about opportunity and risk that apply well beyond the specific industries that shaped them.

The Lion Beneath the Fade by Sebastian Bastian offers that kind of guide, one built to respect the reader’s intelligence, shared with genuine honesty, and structured around frameworks for thinking about opportunity and risk that hold up under real pressure. It rewards readers willing to consider their own path the way someone who has already walked it considers theirs.

If you are ready for an entrepreneurial guide that respects your intelligence, shares its experience with genuine honesty, and gives you frameworks for thinking about opportunity and risk that actually hold up under real pressure, The Lion Beneath the Fade by Sebastian Bastian is waiting for you on Amazon. Pick up your copy and start thinking about your own path the way someone who has already walked it thinks about theirs.

U.S. Worker Displacement Reached 7.4 Million Through 2025

The Bureau of Labor Statistics reported that 7.4 million U.S. workers were displaced from jobs between January 2023 and December 2025. The report includes data on long-tenured workers, reemployment, unemployment and the reasons workers lost their jobs, providing a detailed measure of labor-market displacement.

Key Takeaways

  • The BLS reported 7.4 million displaced workers between January 2023 and December 2025.
  • About 3.3 million displaced workers had been with their employers for at least three years.
  • Among long-tenured displaced workers, 66.1% were reemployed by January 2026.
  • Abolition of a position or shift accounted for 44.4% of long-tenured worker displacement.
  • Manufacturing accounted for the largest share of long-tenured displacement among major industries at 19%.

BLS Reports 7.4 Million Displaced Workers

U.S. worker displacement totaled 7.4 million between January 2023 and December 2025, according to the Bureau of Labor Statistics, with the federal agency reporting separate figures for workers who had longer relationships with their employers. The BLS data provide information on the number of workers affected, their subsequent employment status and the reasons their jobs ended.

The displacement measure covers workers who lost or left jobs under circumstances included in the BLS survey definition of displacement. The reported period extends from January 2023 through December 2025, giving the figures a three-year reference period.

The BLS report separates workers according to their tenure with the employer. Among the 7.4 million displaced workers, 3.3 million had been with their employers for at least three years. The remaining displaced workers had shorter tenure with their employers.

The distinction between overall displacement and long-tenured displacement provides separate measures of job loss. The long-tenured group identifies workers who had maintained employment with the same employer for at least three years before being displaced.

The report also examines the employment status of long-tenured displaced workers after their jobs ended. That information includes workers who were reemployed, unemployed or outside the labor force.

The figures therefore cover more than the number of jobs affected. They also show the subsequent labor-market status of a defined group of displaced workers and identify the circumstances associated with their job losses.

The displacement data can be considered alongside other measures of labor demand, including recent reports on U.S. job openings, which track available positions rather than workers who have already been displaced.

Long-Tenured Workers Account for 3.3 Million Displacements

Long-tenured workers accounted for 3.3 million of the 7.4 million displaced workers reported by the BLS. The agency defines this group based on workers who had been with their employers for at least three years.

The three-year tenure threshold distinguishes longer-serving employees from workers who had spent less time with their employers. This breakdown allows the BLS report to identify displacement among workers with established employment relationships.

The 3.3 million long-tenured workers represented a substantial portion of the total displacement figure. Their outcomes were also tracked separately after displacement, allowing the report to show how many had returned to employment and how many remained unemployed or outside the labor force.

The tenure information is relevant to interpreting the displacement figures because the end of a job held for several years differs from displacement among workers with shorter periods of employment. The BLS report provides the figures without treating all displaced workers as a single group.

The report’s long-tenured category also supports comparisons across reasons for displacement and industries. Position eliminations, plant or company closures or moves, and insufficient work were among the reported circumstances affecting these workers.

Among long-tenured workers, the BLS reported that the abolition of a position or shift accounted for 44.4% of displacement. Plant or company closures or moves accounted for 32.6%, while insufficient work represented 22.9%.

These figures provide a breakdown of the circumstances associated with displacement among workers who had been employed by the same employer for at least three years.

Reemployment Reached 66.1% Among Long-Tenured Workers

The BLS reported that 66.1% of long-tenured displaced workers were reemployed by January 2026. The figure covers the group of 3.3 million workers who had been with their employers for at least three years before displacement.

The reemployment figure provides a measure of the share of long-tenured displaced workers who had obtained another job by January 2026. It does not represent the reemployment rate for all 7.4 million displaced workers.

The BLS also reported that 18.3% of long-tenured displaced workers were unemployed in January 2026. Another 15.7% were outside the labor force.

Together, the figures divide the long-tenured group into three reported labor-market statuses: reemployed, unemployed and outside the labor force. The categories account for the workers included in the long-tenured displacement measure.

The reemployment figure also provides a specific point-in-time measure following the displacement period. The BLS used January 2026 as the reference point for determining the subsequent employment status of long-tenured displaced workers.

The 66.1% figure means that roughly two-thirds of the long-tenured displaced-worker group had returned to employment by that point. The remaining workers were divided between unemployment and being outside the labor force.

The BLS figures therefore distinguish between displacement itself and the employment status that followed. A worker counted as displaced during the 2023–25 period could subsequently be reemployed, unemployed or outside the labor force.

Recent labor data also provide a separate measure of layoffs, including U.S. jobless claims data. Jobless claims and worker-displacement figures measure different aspects of employment conditions and should not be treated as interchangeable statistics.

Position Eliminations Led Major Displacement Reasons

U.S. Worker Displacement Reached 7.4 Million Through 2025

Photo Credit: Unsplash.com

The abolition of a position or shift was the leading reported reason for displacement among long-tenured workers, accounting for 44.4% of cases. The category covers workers whose positions or shifts were eliminated.

Plant or company closures or moves accounted for 32.6% of long-tenured displacement. The category includes displacement associated with a plant or company closing or moving.

Insufficient work accounted for the remaining 22.9% of long-tenured displacement. The figures show the distribution of reported reasons within the long-tenured worker group rather than across all 7.4 million displaced workers.

The three categories provide a breakdown of the circumstances associated with long-tenured worker displacement. Position or shift eliminations represented the largest share, followed by plant or company closures or moves and insufficient work.

The BLS figures also separate the circumstances of displacement from workers’ subsequent employment outcomes. The reason a worker was displaced and whether that worker was later reemployed are therefore distinct measures within the report.

That distinction is important for reading the data accurately. The 44.4% figure describes the reported reason for displacement among long-tenured workers, while the 66.1% figure describes their reemployment status by January 2026.

The report consequently provides several separate measurements of worker displacement: the number of workers displaced, the number with at least three years of tenure, the reason for displacement and the subsequent labor-market status of long-tenured workers.

The distinction between displacement and ongoing hiring can also be seen in recent reporting on U.S. employment and payroll data, which measures changes in employment rather than the specific circumstances recorded in the displacement survey.

Manufacturing Recorded the Largest Industry Share

Manufacturing accounted for 19% of long-tenured worker displacement among the major industries identified in the BLS report. Professional and business services accounted for 16%, while retail trade represented 10%.

The industry figures provide another way to examine the 3.3 million long-tenured displaced workers. Manufacturing had the largest share among the industries specified in the report.

Professional and business services had the second-largest reported share at 16%. Retail trade accounted for 10% of long-tenured displacement.

These industry figures are separate from the reasons for displacement. A worker in manufacturing, for example, could be included in the industry data while also being classified under one of the reported reasons for displacement.

The BLS report therefore provides both industry and circumstance information for understanding the composition of long-tenured worker displacement. The industry percentages identify where the displaced workers were employed, while the reason categories identify the circumstances associated with their job loss.

The January 2026 employment-status figures add another dimension to the report. Of the long-tenured workers affected during the January 2023–December 2025 period, 66.1% were reemployed by January 2026, 18.3% were unemployed and 15.7% were outside the labor force.

The resulting data set connects employment tenure, displacement circumstances, industry and subsequent labor-market status. It provides a detailed statistical account of workers who lost jobs during the three-year period and the status of long-tenured workers after displacement.

Frequently Asked Questions

How many U.S. workers were displaced between 2023 and 2025?

The Bureau of Labor Statistics reported 7.4 million displaced workers between January 2023 and December 2025. The figure covers the full group measured by the BLS displacement report.

How many long-tenured workers were displaced?

The BLS reported 3.3 million displaced workers who had been with their employers for at least three years. This group is separately identified in the report from workers with shorter employer tenure.

What percentage of displaced workers were reemployed?

Among long-tenured displaced workers, 66.1% were reemployed by January 2026. The figure applies specifically to the long-tenured group, not all 7.4 million displaced workers.

What was the leading reason for worker displacement?

Abolition of a position or shift was the leading reported reason among long-tenured displaced workers, accounting for 44.4% of cases. Plant or company closures or moves accounted for 32.6%, while insufficient work accounted for 22.9%.

Which industry recorded the largest share of long-tenured displaced workers?

Manufacturing recorded the largest share among the major industries identified in the BLS report, accounting for 19% of long-tenured displacement. Professional and business services accounted for 16%, and retail trade represented 10%.

AI Won’t Save Your Auto Ads, Governance Will. Here’s the Production Framework That Does.

By Georgette Virgo

For an automotive chief marketing officer, the pressure is no longer simply to make a campaign breakthrough. It is to make a global marketing system work: across 50 or more markets, multiple vehicle lines, dealer networks, legal requirements, media channels, and an unrelenting demand for fresh content. All of it must happen faster, more efficiently, and with a clearer line to sales, consideration, and brand value.

Artificial intelligence (AI) arrived as a promise: faster asset adaptation, more precise audience targeting, lower-cost production, acting as an answer to the global mandate on marketers to do more with less. Where once brands planned for expensive location shoots, crews, and logistics, AI tools can now be used as a faster, cheaper alternative.

The potential has massive appeal, and advertisers are already seeing what happens when quality is managed and measured. According to Integral Ad Science’s data presented at Cannes Lions 2026, brands that prioritized high-quality, high-viewability media environments recorded a 30% lift in brand awareness.

But is it cheaper, really? Any new tool is not typically introduced into an advertising silo, and AI is no exception. The operating reality is more complex: 78% of auto marketers already identify fragmentation across platforms and publishers as a leading challenge, and 85% say orchestration matters even though many lack the systems to coordinate data, decisions, and workflows across their ecosystem.

Introducing a new tool can introduce new complexity. The technology may speed up content creation, but it does not automatically make the system producing that content more adaptable.

For automotive brands, AI will not resolve the lack of integration, fragmented briefs, eliminate duplicate production, or ensure consistent, market-ready assets on its own. Governance will. And it starts with how the organization runs production.

The AI Promise Meets Auto Reality

AI can produce meaningful gains in automotive marketing. A 2026 dealership case study found that an AI-powered lead-scoring program reduced cost per conversion by 28% and increased sales close rates by 15%. But AI doesn’t impact the sales funnel alone.

More broadly, across advertising production, AI can help reduce hours and production costs if high-volume creative generation is matched with structured testing and optimization. That distinction matters for brands under pressure to use AI across the production lifecycle.

For the automotive industry, AI can support audience targeting, creative iteration, previsualization, versioning, localization, editing, and repetitive production tasks. AI is also a clear asset in post-production.

But auto marketers, like many brands, cite a lack of internal expertise, poor data quality or access, and concerns about brand safety and return on investment as central barriers to adoption.

In an industry where product specifications, pricing, safety claims, retail offers, and legal requirements must be accurate across every customer touchpoint, frameworks for content creation are critical. There is also great debate across agency models, with many industry experts questioning agency AI use and cost transparency.

It’s certainly possible for automotive brands to focus in-house and create compelling visuals with generative tools. This involves managing token limits, deciding how assets should move between platforms, establishing naming conventions, and documenting which approaches to repeat or discard.

But for global automotive brands with complex, globally distributed campaign structures, internal adaptation should be considered crucial. Introducing AI into a fragmented system may produce more versions of the wrong asset, with unclear ownership and no dependable connection to campaign performance. If that happens, the speed of creation is no longer an upside.

APR, a global marketing production advisory, recommends an AI production strategy to help their clients implement best practices for AI use across the full 360° production marketing ecosystem. A governed content supply chain with clear workflows, accountable decision-making, and measurable outcomes is a baseline standard beneficial to most any brand. What’s not helpful? Getting into the weeds on what AI can do.

Instead, APR’s production experts recommend brands approach AI with the end goal in mind. “AI is fantastic at efficiency, not necessarily efficiency of cost, but certainly efficiency of speed,” says Russell Sharpe, Head of Production at APR. “The question shouldn’t be ‘How do I use AI?’, but rather ‘Is it the right tool for this product?’

It boils down to choosing the right platform for the right message. Choosing the right platforms is vital for automotive brands struggling to balance the short-term pressure of lead conversion with the long-term necessity of creating future brand demand, as different channels (social media, websites, video platforms) cater to varied audience demographics and engagement levels.

The Governance Gap in Automotive Production

For 2025, the U.S. automotive industry alone had projected media ad spend of roughly $22.5 billion, with a lot of the focus on digital channels and connected TV spending. Automotive advertising has always demanded rigor thanks to legal rules that vary country to country across safety, energy, regulations, complex brand/dealer networks, and the technical requirements of digital platforms, adding more complex layers to content creation.

So while automotive marketers reallocate spending across connected platforms, demand generation, and AI-enabled productions, many still lack the orchestration needed to unify data, decisions, and workflows across their global marketing ecosystems.

A global brand team may own the master platform; regional teams may manage market adaptation; local agencies, production partners, procurement, media teams, and in-house studios may each control a different part of the execution. The result is often duplication, unexpected cost, and lack of accountability, rather than scale. This kind of ecosystem demands governance.

APR recommends that automotive brands institute strict AI governance to safeguard creative budgets and protect brand IP across high-stakes vehicle launches. Automakers should first mandate comparative bidding, running competitive dual-bids to evaluate traditional production against AI workflows, to verify true cost-effectiveness before committing capital.

To eliminate the runaway “token burn” caused by unstructured prompting, marketing teams must enforce strict revision guardrails that lock in agreed-upon review cycles. Finally, contractual transparency must be non-negotiable: brands should require full disclosure of all AI platforms employed, clear line-item breakdowns of AI versus human labor, and explicit legal terms defining IP ownership for every generated visual asset.

The Production Framework That Works

A governed, AI-enabled automotive content supply chain does not begin with selecting a model. It begins with designing the conditions in which that model can create value. For global brands, a practical framework rests on three connected pillars.

1. Design the Operating Model First

Before automating a workflow, brands should define who does what across marketing, brand, procurement, legal, agencies, production partners, and local markets. That means assigning decision rights, agreeing on approval paths, setting standards for source assets and metadata, and identifying where AI has a valid role.

The task is not to create bureaucracy but to remove the ambiguity that leads to rework, duplicate briefs, and delayed approvals. This provides a clear workflow: establish the workflow first, then decide where technology can accelerate it. This creates the foundation for AI to become a repeatable capability rather than a collection of unconnected experiments.

2. Standardize and Compete on Production

Brands need consistent briefs, asset specifications, naming conventions, approval workflows, rights-management practices, and clear production scopes. This enables assets to move safely across markets and channels, supports reuse, and makes production costs transparent.

When a statement of work is clear and comparable, brands can evaluate bids accurately, assess suppliers against relevant benchmarks, and ensure that cost-saving decisions do not undermine creative craft or production quality.

3. Measure Outcomes, Not Just Output

Finally, brands should measure the system’s results, not merely the volume it produces. A content supply chain should track spend, savings, cycle time, asset reuse, supplier performance, revision frequency, launch readiness, and business outcomes alongside traditional production metrics.

This framework converts a familiar challenge into a management advantage: as AI continues to create more possibilities and influence an often-fragmented content production ecosystem, governance determines which possibilities are useful, brand-safe, cost-effective, and scalable.

Governance Is the Competitive Advantage

AI isn’t the flex brands think it is when not coupled with governance across the entire marketing production ecosystem. It will not prevent separate teams from commissioning the same vehicle shoot, resolving conflicting asset versions, or protecting a brand from inconsistent local execution. Without clear governance, it may simply produce those problems at a greater speed.

The automotive brands best positioned for the future will treat AI as part of a governed production system. A framework provides a way to transform AI and fragmented production into a streamlined, measurable system for optimal marketing production performance. The next competitive edge is not the model a company uses, but the operating model it runs.