Economic Insider

At 7% Mortgage Rates, Lori Lane Says the Housing Industry Has to Solve a Different Problem

By: Susan Rogers

Mortgage rates have crossed another psychological threshold.

The Mortgage Bankers Association reported this week that the average contract rate for a conforming 30-year fixed mortgage rose to 7.12% for the week ending September 18, the highest level in more than two years. Mortgage applications declined again, while adjustable-rate mortgages accounted for a growing share of activity.

For an already challenged housing market, 7% matters. But Lori Lane, Founder and CEO of LLANE & Co., says the more important question for builders, brokers and real estate professionals is not when rates will come down.

It is: How do we sell homes successfully if they don’t?

“For several years, the industry has been waiting for rates to normalize, affordability to improve and urgency to return,” Lori Lane said. “At some point, waiting becomes a strategy, and not a particularly good one. Builders should plan their 2026 and 2027 strategies around the market they have, not around an assumption that 5% mortgage rates are just around the corner.”

Atlanta is showing what happens when affordability pressure collides with a lack of buyer urgency.

The latest Georgia MLS numbers illustrate the challenge. Across the 29-county Atlanta metropolitan area, 4,655 residential properties went under contract in August, down 26.6% from the same month last year. Closed sales declined 3.2%, while active listings increased 3.6%.

Within the 12-county Atlanta Core market, pending sales fell 28.9% year over year.

“There are homes available, sellers who want to sell, builders who want to build and consumers who still want to move,” Lane said. “What is missing is enough conviction to make many buyers act. That makes this more than an inventory or affordability problem.”

Not every hesitant buyer has the same problem.

Lane says the industry needs to distinguish among three very different consumers.

“Some buyers simply cannot afford today’s payment,” Lane said. “Higher rates have reduced their purchasing power, and better sales technique cannot change the math.”

Others can afford to purchase but dislike the financial proposition. They may have substantial income or equity, yet borrowing at 7% feels unattractive compared with the mortgage they already have.

Then there are buyers who can afford the home and may even want it, but are afraid of making the wrong decision.

“What if rates fall after I buy? What if prices decline? What if I cannot sell my current home? What if waiting produces a better deal?” Lane said. “Those are not qualification problems. They are confidence problems, and they require a different sales and marketing response.”

Financing has become part of the product.

New-home builders have tools that individual resale sellers often do not. According to recent Realtor.com research, 18.8% of new-construction listings offered a buyer incentive in August, with reduced mortgage rates appearing on 13.8% of listings and an average of close to 4%.

On a $450,000 home with 20% down, Realtor.com calculated that the difference could reduce principal and interest by more than $600 per month.

“That changes the new-construction-versus-resale conversation,” Lane said. “Buyers should evaluate more than the purchase price. The comparison should include monthly payment, cash required at closing, incentives, maintenance, warranties, energy efficiency and the cost of updating an older home.”

She added, “Builders increasingly are not just selling the house. They are selling the financial structure that makes the house attainable.”

Incentives alone are not a strategy.

“The same incentive will not solve every buyer’s objection,” Lane said. “A younger buyer with limited cash may respond to a rate buydown or closing-cost assistance. A move-up buyer may need help selling an existing home. An active-adult buyer may have substantial equity but hesitate to exchange a 3% mortgage for a 7% mortgage. A luxury buyer may care less about the rate than whether the home, location, service and lifestyle justify making a move.”

For Lane, the question should not simply be, “What incentive are we offering?”

It should be, “What is preventing this buyer from saying yes?”

“Answering that requires better qualification, stronger discovery and a more sophisticated sales conversation,” Lane said.

The sales presentation has to change with the market.

“In a fast-moving market, inventory and rising prices create urgency,” Lane said. “Today’s buyers often have more time, information and choices. Builders and sales teams have to create clarity where the market no longer creates urgency.”

Instead of moving immediately from product presentation to incentives, Lane says sales teams should be asking different questions.

What monthly payment feels comfortable?

What needs to happen with the existing home?

Is the concern financial, or is it uncertainty?

What would make moving now more valuable than waiting?

“The answers should determine the strategy,” Lane said. “For some buyers, that may be a rate buydown. For others, it may be help navigating the sale of an existing home. For still others, the solution may be demonstrating the lifestyle, convenience, location or long-term value well enough to make the move feel worthwhile.”

New construction has an opportunity.

“A difficult housing market does not eliminate opportunity. It changes where opportunity lies,” Lane said. “Builders can structure financing, adjust inventory, package incentives, offer warranties and deliver move-in-ready homes. They can also create lifestyle and amenity experiences that individual resale sellers cannot replicate.”

But those advantages matter only if consumers understand them.

“Marketing has to translate incentives into real-life value,” Lane said. “Sales teams have to distinguish affordability objections from confidence objections, and builders have to become more precise about where they spend incentive dollars.”

“The winners may not be the builders offering the largest discounts,” Lane added. “They may be the ones that understand why their buyers are hesitating and solve that specific problem better than anyone else.”

Mortgage rates will eventually change, but Lane says builders cannot base today’s strategy on waiting for tomorrow’s market.

“At 7%, the question is no longer when the market will rescue us,” Lori Lane said. “It is what we are willing to change while we wait.”

U.S. Jobless Claims Fall to 197,000 in Latest Report

U.S. jobless claims fell to 197,000 for the week ending September 19, according to the Labor Department, marking the lowest level since mid-July. The decline came as layoffs remained limited, providing a fresh reading on labor-market conditions ahead of the next monthly employment report.

Key Takeaways

  • Initial unemployment claims fell to 197,000 for the week ending September 19.
  • The latest reading was the lowest since mid-July.
  • The four-week moving average declined to 202,250.
  • Weekly claims remained below 220,000 for most of 2026.
  • The data provide a current measure of layoffs before the next monthly employment report.

U.S. Jobless Claims Fall to 197,000

U.S. jobless claims fell to 197,000 in the week ending September 19, according to data from the U.S. Department of Labor, as applications for unemployment benefits reached their lowest level since mid-July.

The latest figure declined from a revised 198,000 claims in the previous week. The weekly total measures the number of people filing initial applications for unemployment insurance and provides a current indication of layoffs.

The decline leaves initial claims at a level that indicates relatively few workers were entering unemployment through new benefit applications. Weekly claims had remained below 220,000 for most of 2026, according to the reported data.

The latest result was released ahead of the next monthly employment report, giving economists and businesses another measure of labor-market conditions between monthly employment releases.

Recent data on the broader U.S. labor market conditions have also covered employment, hiring and unemployment measures, providing additional context for interpreting weekly claims.

Initial claims can move from week to week, making the four-week moving average another measure used to assess underlying conditions. The latest average also declined during the week.

Four-Week Claims Average Declines to 202,250

The four-week moving average of initial claims fell to 202,250 from 204,000 in the previous week. The average reduces the effect of weekly fluctuations and provides a smoother measure of new unemployment-benefit applications.

The decline in the average accompanied the drop in the weekly claims figure. Both measures therefore moved lower in the latest report.

The Labor Department’s weekly claims data cover initial applications filed through state unemployment insurance systems. The measure does not count every unemployed person because eligibility, filing behavior and participation in unemployment insurance programs can differ among workers.

Continuing claims provide a separate measure by tracking people who remain on unemployment benefits after an initial application. Initial claims instead provide information about new entries into unemployment insurance.

The distinction allows the weekly report to provide information about both new layoffs and the number of people continuing to receive benefits. The latest report’s headline movement was in initial claims, which declined to 197,000.

Earlier U.S. jobless claims data also showed how weekly applications can provide a separate view of layoffs from monthly employment measures.

Weekly claims also provide more frequent information than monthly employment measures. A change in claims can therefore offer an early indication of changes in layoffs before those conditions appear in broader monthly labor statistics.

Layoff Activity Remains Limited Across the Labor Market

The low level of initial claims indicates that new applications for unemployment benefits remained limited during the week ending September 19.

Employers’ decisions to reduce payrolls can affect initial claims when eligible workers apply for unemployment benefits after losing their jobs. A low claims reading therefore provides information about the number of workers entering unemployment through covered layoffs.

The latest reading does not measure total employment or the number of jobs created during the week. It measures initial unemployment-benefit applications, making it a narrower indicator of labor-market conditions.

The distinction is important because an economy can experience low layoffs while hiring activity changes. Initial claims therefore provide information about one side of labor-market turnover rather than a complete measure of employment.

The latest U.S. worker displacement data provide a separate measure of workers who lost jobs over a longer period and therefore differ from weekly unemployment-benefit claims.

The distinction between the two measures is important. Weekly initial claims track new applications for unemployment benefits, while displacement data cover workers who lost jobs during a specified multi-year period.

The claims data also need to be considered alongside the four-week average. The decline in both measures provides a more consistent reading than a change in the weekly figure alone.

Claims remained below 220,000 for most of 2026, according to the reported data. The September 19 reading was below that level and also represented the lowest weekly figure since mid-July.

For businesses, low claims can indicate that relatively few workers are entering unemployment through new benefit applications. For workers, the measure provides a weekly indication of layoffs covered by state unemployment insurance systems.

Hiring Continues at a Slower Pace

The latest claims report provides information about layoffs but does not establish the pace of hiring. Hiring and layoffs are separate components of labor-market activity and can move differently.

The reported labor-market conditions show a period in which new unemployment-benefit applications remained low even as job creation had become slower than during stronger employment periods.

A slower pace of hiring can coexist with limited layoffs because employers may reduce the number of new positions they fill without making large-scale reductions to existing workforces.

That distinction matters when interpreting weekly claims. A low number of initial applications does not mean that hiring is accelerating, nor does it measure the number of job openings available to workers.

The claims data instead provide a near-term measure of job losses entering the unemployment insurance system. Other Labor Department releases provide information on employment, wages, job openings and other parts of the labor market.

The timing of the latest report also makes it relevant to the next monthly employment release. Weekly claims offer a more frequent measure that can be compared with monthly employment figures as they become available.

Businesses can use labor-market indicators to assess workforce conditions, while economists can compare claims with other measures of employment and unemployment. The weekly series is released more frequently than monthly labor-market reports.

Jobless Claims Provide Fresh Labor-Market Data

The September 19 claims report adds another weekly observation to the U.S. labor-market data series. The 197,000 initial claims figure was lower than the revised 198,000 reported for the previous week.

The four-week average also declined to 202,250. That movement provides a second measure of claims activity and reduces the influence of any single week’s result.

The latest reading was the lowest since mid-July, according to the reported figures. Weekly claims had remained below 220,000 for most of 2026.

Initial claims are one of several measures used to monitor employment conditions. The figure captures new unemployment-benefit applications, while continuing claims measure people who remain on benefits.

The data can also be viewed alongside monthly employment figures. Monthly reports provide information on payroll employment and unemployment, while weekly claims offer more frequent information about workers entering unemployment insurance.

The September 19 figure therefore provides a current measure of layoffs ahead of the next monthly employment report. Its movement, together with the four-week average, shows that new unemployment-benefit applications remained low during the latest reporting week.

Frequently Asked Questions

What are U.S. jobless claims?

U.S. jobless claims are applications for unemployment benefits filed by workers through state unemployment insurance systems. Initial claims measure new applications and provide a weekly indicator of layoffs covered by the programs.

How many unemployment claims were reported for September 19?

There were 197,000 initial unemployment claims for the week ending September 19. The figure was down from a revised 198,000 in the previous week.

When were U.S. jobless claims last this low?

The September 19 reading was the lowest weekly level since mid-July. The four-week moving average also declined to 202,250.

What does the latest claims data show about layoffs?

The 197,000 initial claims figure indicates that new applications for unemployment benefits remained limited during the reporting week. The measure focuses on new claims rather than total unemployment or overall employment.

How are weekly jobless claims used to assess the labor market?

Weekly claims provide a frequent measure of new unemployment-benefit applications and can indicate changes in layoffs. The four-week moving average helps reduce the effect of week-to-week fluctuations.

Mathematical Thinking Is a Life Skill, Even If You Never Use Algebra Again

By: Audrey Denise B. Cachuela

Ask a nine-year-old to solve a word problem and watch the pencil stop moving, like there’s a trick buried in the sentence. Fast-forward twenty years. Hand that same person a lease to sign and a job offer with three competing pay structures, and they stall the same way. Same hesitation, older paperwork.

Spirit of Math has built its classrooms around that specific hesitation for more than thirty years. Kim Langen, the company’s CEO and co-founder, structured the program around a simple bet: a kid who learns to approach something unfamiliar ends up further ahead, long after graduation, than a kid who just memorized more formulas.

Say “math education” to most people, and they picture grades, formulas, the dread of a timed quiz. Mathematical thinking is the reasoning underneath the numbers, and it has almost nothing to do with sitting at a desk doing computation. It’s what lets someone compare two job offers with different benefits packages, guess honestly at how long a renovation will take, or catch a headline statistic that doesn’t mean what it claims to mean.

What Mathematical Thinking Actually Looks Like in Everyday Life

A budget looks like arithmetic until you actually build one. Most of the work happens before a single number gets added up: figuring out what’s a need versus a want you’ve talked yourself into, noticing the cost that quietly drains an account every month, leaving slack for whatever goes wrong. Deciding what to measure is harder than doing the math itself.

Something breaks, and nobody knows why, and that’s a different kind of problem. A laptop glitches, a car won’t start, a recipe comes out wrong for reasons nobody can name, and the process is always the same: isolate one variable, change it, see what happens, rule out what didn’t work. Nobody calls that math, but it’s the identical move a student makes tracing back through a proof to find where it went wrong. The same instinct applies when a headline statistic gets quoted without a sample size attached: the useful question is what the number is actually built on. The OECD defines mathematical literacy along these lines, as the capacity to reason with numbers and apply that reasoning to real judgment calls in personal, civic, and professional life (Source: PISA Mathematics Framework, 2023).

Why the Reasoning Outlasts the Formula

Ask an adult to recite the quadratic formula and most will draw a blank. That’s fine, because the formula was never the point. What sticks is knowing which kind of question you’re facing before reaching for any tool, and that judgment doesn’t expire the way a formula does.

A student who only learned to copy a method freezes when the wording changes or the setup looks unfamiliar. Someone who understands why the method works has more options: hunting for a similar problem solved before, isolating what’s missing, shrinking the problem down to something manageable. That same move shows up later, breaking down a dense paragraph in a history essay or tracking a bug through a hundred lines of code.

Checking your own answer matters just as much as finding one. A restaurant bill of six thousand dollars for a table of four should raise an eyebrow immediately, and so should a delivery estimate of three minutes for a cross-country package. Catching that kind of error in your own work eventually stops feeling like an extra step and becomes automatic.

Breaking Problems Down Becomes a Habit

A big problem feels impossible before anyone’s started, usually because too many questions are competing for attention at once. Picture a kid working through a dense word problem: write down what’s known, name what’s missing, pick one manageable step, and let whatever comes out of it feed the next one. If the approach falls apart somewhere along the way, there’s still enough structure left to find exactly where, instead of scrapping everything and starting over.

The same sequence gets a teenager through a major assignment, minus most of the crying. “Finish the project” turns into stages, each with its own rough deadline, which also makes starting less painful: a single enormous task invites procrastination just by existing, while a staged version invites action because the first step is small enough to actually attempt. Years later, that identical process resurfaces at work, planning an event or managing a team that’s fallen behind. The Education Endowment Foundation frames this kind of metacognitive strategy as helping students plan, monitor, and evaluate their own learning while they work, and finds it lands best when teachers build it into subject lessons rather than treating it as a separate add-on (Source: Metacognition and Self-Regulated Learning, 2025).

Teaching Math So the Thinking Actually Sticks

Fluency and understanding train different things. Showing a student a procedure once and handing them a worksheet of near-identical problems builds speed at copying it. Real understanding comes from deciding when a piece of knowledge applies and why, which is a judgment call, not a memory exercise. Asking “How do you know?” instead of “What’s the answer?” forces a student to lay out their reasoning in an order someone else can follow, and when a classmate lands on a different answer, both students end up tracing back to find exactly where their thinking diverged. An Ofsted subject report draws a similar line, separating practice that builds speed and accuracy from the more exploratory work of explaining relationships and reasoning, and concludes classrooms need both (Source: Coordinating Mathematical Success: The Mathematics Subject Report, 2023).

Inside the Classroom: How This Plays Out at Scale

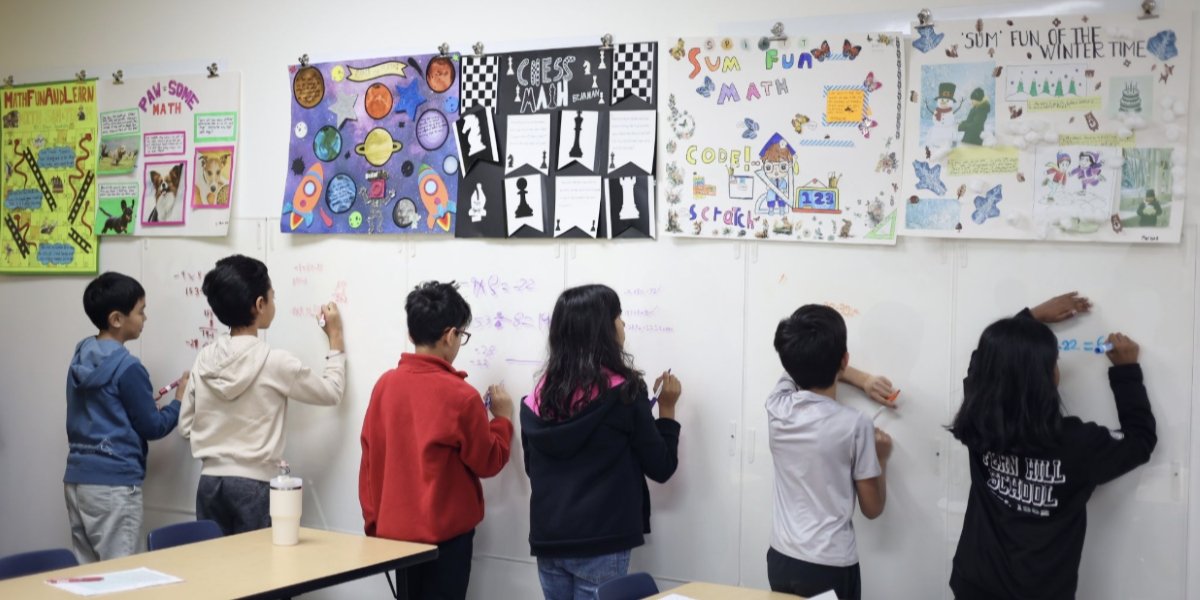
Walk into a Spirit of Math classroom, and this premise stops being abstract. Students spend their time interpreting a question, testing approaches, and putting their reasoning into words someone else can follow, with the right answer as only part of what’s happening in the room. The program layers core curriculum, drills, problem solving, and group work together, and teachers complete more than one hundred hours of training before they ever work with a student. Close to nine hundred Spirit of Math students landed placements on national mathematics honour rolls in one recent year, across 35+ campuses.

No school can hand a kid a pre-written answer for every situation waiting for them down the road. A strong math education gives them a reliable way to approach whatever question nobody saw coming, whether it shows up on a test, inside a budget, or in a decision that has nothing to do with numbers at all.

If you want your child building that kind of reasoning well past worksheets and test scores, Spirit of Math offers placement interviews to help find the right in-person or online program, one that gives kids regular practice solving, explaining, and defending problems that are genuinely difficult.