Economic Insider

Alexander Hykel of Merrill Lynch on Building Trust and Transparency in Financial Advisory Relationships

Financial planning is rarely just about numbers. Behind decisions about retirement, investments, taxes, and estate planning are personal priorities that can look very different from one individual or family to the next. Understanding those priorities is an important part of creating a financial strategy that reflects a client’s broader goals.

Alexander Hykel, a financial advisor at Merrill Lynch, has spent more than 13 years working in financial services. With a background in economics and experience across major financial institutions, Hykel has developed an approach centered on understanding the individual behind the portfolio.

Rather than beginning solely with investments or performance expectations, effective financial planning requires a broader understanding of a client’s circumstances, financial experience, risk tolerance, short- and long-term objectives, and definition of financial security.

For Hykel, those considerations form the foundation of a strong advisory relationship.

Looking Beyond the Numbers

Hykel’s interest in financial services began with a curiosity about economics, investing, and the ways wealth can grow over time. His economics background provided a foundation for understanding markets, risk, and long-term financial decision-making.

Over the course of his career, however, his perspective has expanded beyond the technical aspects of investing.

Financial decisions do not happen in isolation. They are influenced by family responsibilities, career plans, previous experiences with money, personal attitudes toward risk, and expectations for the future. Two clients with similar financial profiles may therefore require very different approaches.

Understanding that distinction is an important part of personalized financial guidance.

For some individuals, financial security may mean retiring comfortably without worrying about outliving their savings. For others, it may mean creating a meaningful inheritance for their children, preparing for unexpected circumstances, or developing a more tax-conscious approach to managing wealth.

The numbers provide important information, but they are only one part of the larger financial picture.

Starting With the Client’s Priorities

A strong financial strategy begins with understanding what the client is ultimately trying to accomplish.

That includes examining how someone has historically approached financial decisions, how comfortable they are with investment risk, what previous investing experience they have, and which financial concerns are most important to them.

Several questions frequently sit at the center of long-term financial planning:

  • Will retirement savings be sufficient, and how long will those assets need to last?
  • What assets may eventually be passed to family members or future generations?
  • Are there tax planning strategies that should be considered as part of the broader financial picture?
  • How would a family’s finances be affected by an unexpected life event?

Questions like these help transform financial planning from a generalized exercise into a strategy built around an individual’s actual circumstances.

They also reinforce the importance of looking beyond immediate market performance. While investment results matter, long-term planning often involves balancing multiple priorities at the same time, including retirement, wealth preservation, family considerations, risk management, and legacy planning.

Transparency as the Foundation of Trust

Trust is especially important in financial advisory relationships because clients are making decisions that may affect decades of their lives.

Transparency plays a central role in establishing that trust.

Clients should have a clear understanding of the strategies being discussed, the risks involved, applicable fees, and the reasoning behind recommendations. Clear communication can help individuals participate more confidently in the financial planning process rather than feeling removed from decisions involving their own assets.

For Hykel, transparency and compliance are not separate from building a strong client relationship. They can reinforce it.

Providing information clearly and documenting important aspects of the advisory relationship can create greater alignment between advisor and client. It also helps establish realistic expectations about risk, performance, and the long-term nature of financial planning.

The goal is not simply to develop a financial strategy. It is to help clients understand the strategy and the considerations behind it.

Experience Across the Financial Services Industry

More than a decade in financial services has also given Hykel exposure to different business models, investment environments, and approaches to client service.

That experience can provide valuable perspective.

Financial institutions may differ in the tools, resources, technology, and investment solutions available to advisors. Working within different environments can help an advisor better understand how those resources fit into the larger responsibility of serving clients.

Hykel’s career has ultimately reinforced the importance of keeping the client’s objectives at the center of the planning process.

His work in South Florida has further shaped that perspective. Developing relationships throughout the region has allowed him to work with individuals, families, professionals, and business owners with varying financial priorities and stages of life.

Those relationships underscore an important reality of financial planning: there is rarely a universal definition of financial success.

Continuing to Build Expertise

The financial services industry continues to evolve as markets change, technology advances, regulations develop, and new planning tools become available. Continuing education is therefore an important part of maintaining a thoughtful advisory practice.

Hykel is pursuing the Certified Financial Planner designation as part of his continued professional development. The CFP curriculum encompasses areas including financial planning, retirement, tax considerations, estate planning, risk management, and professional ethics.

His longer-term goals also include strengthening his presence in South Florida while continuing to develop broader professional visibility.

At the same time, financial education remains an area of personal importance. Hykel has been involved with Habitat for Humanity and financial literacy efforts designed to help low-income families better understand money management and financial decision-making.

That work reflects a broader principle: access to financial knowledge can be valuable at every income and wealth level.

A Relationship-Driven Approach to Financial Guidance

Technology has changed how people invest, track their finances, and access information. Yet the human side of financial planning remains difficult to replace.

Understanding someone’s priorities requires more than reviewing account balances. It requires learning how that person thinks about money, what risks they are comfortable taking, what responsibilities they carry, and what they ultimately want their financial resources to accomplish.

Hykel’s approach at Merrill Lynch reflects several principles that can contribute to stronger long-term advisory relationships: understanding the individual before developing the strategy, communicating risks and expectations clearly, maintaining transparency around financial decisions, and continuing to build expertise as the industry evolves.

Ultimately, effective financial guidance is not simply about managing investments. It is about helping individuals and families make informed decisions within the context of the lives they are working to build.

For Alexander Hykel, that means keeping the client’s goals, circumstances, and long-term financial well-being at the center of the relationship.

Disclaimer: This article is for informational purposes only and does not constitute financial, investment, tax, or legal advice. Readers should consult an appropriately qualified professional regarding their individual circumstances.

Fed Plans Five-Region Bank Supervision Overhaul

Federal Reserve Vice Chair for Supervision Michelle Bowman announced plans to reorganize U.S. bank supervision into five geographic regions led by regional leaders. The central bank also plans to review fixed asset thresholds that determine when banks face stricter capital, liquidity and stress-testing requirements.

Key Takeaways

  • The Federal Reserve plans to establish five geographic regions for bank supervision.
  • Each region will have a designated leader overseeing supervisory activity.
  • Regional Reserve Bank staff will continue conducting bank examinations.
  • Bowman plans to begin interviewing candidates for regional leadership positions early next year.
  • The Fed will consider updating fixed-dollar asset thresholds and potentially adjusting them every five years for inflation and economic growth.

Federal Reserve Plans Five Regional Bank Supervision Areas

The Federal Reserve plans to replace its existing bank-supervision structure with five geographic regions, according to the plan announced by Bowman. Each region will have a regional leader responsible for overseeing supervisory activity.

The proposed structure changes the organization of responsibility rather than removing the regional Reserve Banks from the examination process. Staff at those Reserve Banks will continue conducting supervision of banks under the new arrangement.

The five-region model is intended to establish a clearer line of responsibility for supervisory decisions. Bowman said the Federal Reserve’s supervisory function will be realigned around accountability and clear decision-making authority.

The restructuring follows concerns about the way responsibilities are divided under the current arrangement. Federal Reserve officials in Washington currently establish bank examination policy, while supervision is carried out through the central bank’s 12 regional Reserve Banks.

Recent lending data have also shown that bank credit remains an important part of the U.S. financing system, including for financial institutions operating outside traditional deposit-taking banks. That relationship is examined in recent analysis of bank lending standards.

Under the proposed model, regional leaders will have responsibility for supervisory activity within their assigned areas. The change therefore creates a new layer of regional leadership while retaining examination staff at the regional Reserve Banks.

Regional Leaders to Oversee Supervisory Activity

The Federal Reserve plans to appoint leaders for each of the five new regions. Bowman said interviews for those positions are expected to begin early next year.

The regional leaders will oversee supervisory activity conducted by Reserve Bank staff. Their responsibilities will include providing leadership over the supervisory work performed within their respective regions.

The planned appointments create a defined leadership structure between the Federal Reserve’s Washington-based supervisory function and examination staff operating through the regional Reserve Banks.

The existing system divides supervisory work across the Federal Reserve’s 12 districts. The proposed five-region structure will consolidate those geographic responsibilities under fewer regional leaders.

The examination function itself will remain regional. Reserve Bank personnel will continue carrying out bank supervision, while the new leaders will provide oversight for the work within each region.

Bowman’s announcement also establishes a future timeline for the organizational change. The leadership selection process is expected to begin with interviews early next year rather than immediately changing the personnel responsible for each region.

Federal Reserve policy decisions have also remained closely watched by businesses and financial professionals. Earlier reporting on Fed rate hike expectations provides additional context on the central bank’s broader policy environment.

Fed Seeks Clearer Accountability in Bank Examinations

The Federal Reserve’s proposed structure is tied to Bowman’s concerns about accountability within bank supervision. She said the current arrangement can weaken the connection between responsibility and accountability when supervisory concerns arise.

Bowman also criticized the Federal Reserve’s use of committees in the supervision process. She said committees could delay decisions and make responsibilities less clear among central bank staff.

The proposed structure is designed to give regional leaders clearer responsibility for supervisory activity. That would establish a more direct chain of authority for the work carried out by regional examination teams.

The issue of supervisory accountability is also connected to the Federal Reserve’s review of its handling of bank risks. The proposed reorganization follows an independent review of the collapse of Silicon Valley Bank that examined the actions of Federal Reserve examiners.

That review found that Fed examiners had been slow to take action, according to Bowman’s remarks. The finding has informed the discussion around clearer supervisory responsibility.

Under the new arrangement, regional leaders would oversee the supervisory activity performed by Reserve Bank staff. The change therefore addresses the organizational structure surrounding examinations rather than replacing the regional examination workforce.

The Federal Reserve’s plan also seeks to streamline decision-making. Bowman’s criticism of committee structures focuses on the allocation of responsibility when examiners identify risks at banks.

The central bank has undertaken other reviews of its institutional framework. A separate Federal Reserve review has involved changes to the central bank’s policy framework, although that work concerns monetary-policy operations rather than bank supervision.

Asset Thresholds Face Potential Regulatory Updates

The Federal Reserve also plans to consider changes to fixed-dollar asset thresholds that determine when banks become subject to stricter regulatory requirements.

Those thresholds can affect requirements involving capital, liquidity and stress testing. The Fed is considering a mechanism that would update fixed-dollar thresholds every five years to account for inflation and economic growth.

The proposed approach would change how asset thresholds are maintained over time. Fixed dollar amounts can become less reflective of changes in the size of the economy as prices and economic activity increase.

Banks have argued that fixed asset thresholds can eventually apply stricter requirements to institutions that have grown with the broader economy but have not necessarily changed in the ways originally targeted by enhanced supervision.

The Federal Reserve’s review therefore covers both the level of the thresholds and the possibility of establishing a recurring adjustment process.

Bowman said the Fed would consider the updated thresholds later this year. The proposal does not itself change the thresholds immediately.

The asset-threshold review is separate from the creation of the five geographic supervision regions, but both initiatives concern the structure through which the Federal Reserve oversees banks.

The threshold system determines when additional regulatory requirements can apply based on a bank’s assets. The proposed review would examine whether those fixed levels remain appropriate and whether they should be adjusted periodically.

New Supervisory Structure Moves Toward Implementation

The proposed five-region structure will require the Federal Reserve to establish the new regional leadership positions before the arrangement is fully implemented. Bowman said the central bank expects to begin interviewing candidates early next year.

Regional Reserve Bank staff will continue performing supervisory work under the planned structure. The principal organizational change is the creation of five regional leaders with responsibility for overseeing that activity.

The Federal Reserve will also consider changes to the asset thresholds later this year. A five-year adjustment mechanism tied to inflation and economic growth is among the approaches under consideration.

The two changes affect different parts of U.S. bank regulation. The regional restructuring addresses supervisory organization and accountability, while the threshold review concerns the regulatory requirements that can apply as banks grow.

The planned changes also preserve the role of the Federal Reserve’s regional banks in conducting examinations. The new leadership structure is intended to provide a different allocation of responsibility for that work.

The timing of the proposals means that the supervisory leadership process and the asset-threshold review will develop on separate timelines. Regional leadership interviews are expected to begin early next year, while the Fed plans to consider the threshold changes later this year.

The proposed five-region system therefore represents an organizational change that will be implemented through new regional leadership, while the asset-threshold review could alter the criteria used to determine when banks face stricter regulatory requirements.

Frequently Asked Questions

What is the Federal Reserve’s new bank supervision structure?

The Federal Reserve plans to organize bank supervision into five geographic regions. Each region will be led by a regional leader responsible for overseeing supervisory activity conducted by regional Reserve Bank staff.

How many regions will the Fed use for bank supervision?

The proposed structure includes five geographic regions. The current system uses the Federal Reserve’s 12 regional Reserve Banks to conduct bank supervision.

Who will oversee the new Federal Reserve supervision regions?

Each of the five regions will have a designated regional leader. Michelle Bowman said the Federal Reserve plans to begin interviewing candidates for those positions early next year.

Will regional Reserve Banks continue conducting bank examinations?

Yes. The proposed restructuring does not remove regional Reserve Bank staff from the examination process. Those staff members will continue conducting supervisory activity under the new regional leadership structure.

Are Federal Reserve bank asset thresholds changing?

The Federal Reserve plans to consider updates to fixed-dollar asset thresholds later this year. The central bank is also considering a mechanism that would adjust those thresholds every five years for inflation and economic growth.

UltimateTax Is the Professional Tax Software Company Helping Preparers Work Smarter

An Efficiency Story Rooted in Iowa

Muscatine, Iowa, isn’t typically associated with software innovation. Yet, UltimateTax has been building professional tax tools there since 2006, quietly growing into a platform used by over 50,000 tax preparers nationwide. The company’s appearance on the Inc. 5000 list of fastest-growing private companies, where it ranked 24th in Iowa and 4,194th nationally, marked an external acknowledgment of that progress.

The story of UltimateTax is, at its core, a story about operational efficiency. Tax preparation is an industry where time is the defining constraint. During peak season, a preparer’s ability to move through returns accurately and quickly determines how many clients they can serve, how much they can earn, and how much stress they carry through a three-month sprint. UltimateTax was built to improve all three.

Interview-Style Entry and Smart Diagnostics

The platform’s architecture removes friction from the preparation workflow. Interview-style data entry guides the preparer through a client’s information in a structured sequence, reducing the cognitive load of manually moving between forms. Smart diagnostics run in the background, flagging potential issues before submission. Context-sensitive help appears within the workflow itself, so preparers don’t have to pause their work to search for answers.

Web-based professional tax software options enable preparers to work more efficiently regardless of where they or their clients are located. UltimateTax’s Online 1040 package delivers the full platform in a browser, no installation required, and automatic updates. Access from any device with internet connectivity means that a practitioner working from a client’s location or a satellite office isn’t working with a degraded toolset.

Pricing Built for Real Practices

The true cost of tax preparer software depends on more than the initial purchase price. Renewal pricing and software costs that scale with filing volume both influence long-term value.

UltimateTax’s renewal pricing is lower than new-customer pricing, creating a compounding cost advantage over time.

The company’s pay-per-return tax software option offers a model for practices needing flexibility. With no installation and up to 10 users included, this tier allows preparers to match their software expenditure to volume. For a practice that processes a lower and more variable number of returns from year to year, this removes an element of financial uncertainty.

The flat-fee packages, Desktop 1040, Online 1040, and 1040+ Corporate, provide unlimited e-filing and unlimited users for practices with higher, more predictable volume. The 1040+ Corporate package, combined with the Partnership (1065) and S-Corporation (1120S) forms, gives preparers serving business clients one platform that handles both personal and business returns.

Support Built for Tax Professionals

The productivity cost of a downed software system during peak filing season is not only a technology problem. It’s also an economic one. A preparer who can’t access their platform for several hours during the February-to-April window can miss deadlines, lose client confidence, and absorb the administrative cost of rescheduling appointments.

UltimateTax’s 365 customer service addresses this risk. The company’s US-based support crew is available year-round and specifically trained on the UltimateTax platform. When a preparer reaches support with a complex issue, the person responding is not reading from a script. The team understands the software well enough to handle unusual scenarios efficiently.

UltimateTax software reviews from preparers cite support quality as a distinguishing factor, particularly compared with platforms where support is outsourced or limited to peak season. For a small practice with no internal IT function, knowing that reliable help is available whenever issues arise reduces operational risk and keeps work moving.

The Cost of Switching Software

For preparers currently on competing platforms, the economic calculation of switching also includes the cost of migrating existing data. UltimateTax removes this barrier with free data conversions from many other tax software brands.

A practice that has been on a legacy platform for 10 years holds significant client data that would take considerable time to rebuild manually. The ability to migrate existing client data can transform switching software from a costly undertaking into a financially practical decision, particularly when long-term pricing also favors UltimateTax.

Positioned for Where the Industry Is Going

Tax preparation software is moving toward cloud-based delivery. UltimateTax has been building its online platform to match that trajectory. The addition of Forms 1065 and 1120S to the online platform, with Mac support for corporate returns included for the first time, represents a deliberate move toward a fully online offering without abandoning desktop preparers who depend on that model.

For preparers making a technology investment decision with long-term implications, UltimateTax offers a platform with a demonstrated growth record, a support model built for the realities of a tax practice, and a pricing structure designed to reduce the total cost of professional-grade software over time.

Disclaimer: This article is for informational purposes only and does not constitute tax, legal, financial, or accounting advice. Software features, pricing, availability, and tax forms may change over time. Tax professionals should independently evaluate software options and consult applicable IRS guidance, state requirements, and qualified professional advisers when necessary.

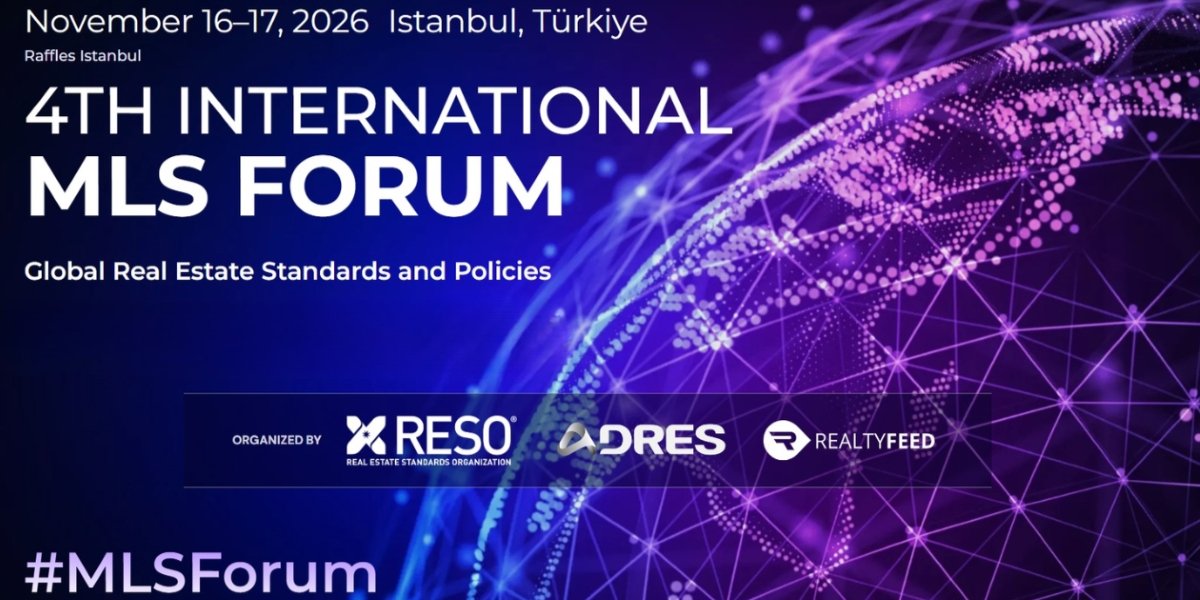
FIABCI Joins Global Data Exchange Ahead of 4th International MLS Forum in Istanbul, November 16-17

The forum, organized by RESO, ADRES and RealtyFeed, will center on cross-border data sharing through the Global Data Exchange (GDX).

October 2026, Istanbul, Türkiye: FIABCI, the International Real Estate Federation, has joined the Global Data Exchange (GDX), the strategic initiative for standardized, cross-border sharing of listing data that anchors this year’s 4th International MLS Forum (IMLSF). The forum takes place November 16-17, 2026, at Raffles Istanbul. FIABCI’s participation extends GDX’s reach to real estate businesses, associations and professionals across global markets.

Now in its fourth consecutive year, the forum connects MLS leaders, regulators, real estate associations, brokerage executives, proptech companies and standards organizations to share the standards, technology and business practices that support more transparent, cooperative and efficient property marketplaces for the communities they serve. Attendees will take part in the conversations shaping how property information is shared, accessed and trusted across borders.

The forum is organized by the Real Estate Standards Organization (RESO), Advanced Real Estate Services (ADRES) and RealtyFeed. Universal Consulting Opportunities (UCO) serves as Title Partner, and TÜGEM Türkiye, a national real estate organization with more than 2,000 members, serves as local host.

Confirmed speakers include Lily Chang, World President of FIABCI; Merri Jo Cowen, Inaugural President of GDX, Executive Vice President of UCO and Chief Vision Officer of Stellar MLS; Sam DeBord, CEO of RESO; and Jeremy Crawford, President and CEO of First Multiple Listing Service (FMLS), among others.

Last year’s edition welcomed more than 200 industry professionals from 51 countries. Istanbul, which links Europe and Asia, offers convenient access for delegates from Europe, Asia, Africa and the Middle East.

“We’re delighted to reconvene some of the industry’s leading experts from across the real estate marketplace, at the intersection of technology, real estate data, governmental bodies and more,” said Merri Jo Cowen, Inaugural President of GDX. “We have some great speakers, and I look forward to paving the way for the future of real estate data with such a dynamic and empowered group of professionals.”

Special hotel rates at Raffles Istanbul are available for registered attendees, with booking details provided in the registration confirmation email. Registration is open at mlsforum.org.

About the International MLS Forum: The International MLS Forum is an annual gathering of organized real estate marketplaces, standards bodies and technology leaders working to improve how property information is structured, shared and trusted worldwide. Held in Paris (2023), Milan (2024) and Toronto (2025), the forum brings together participants from more than 50 countries. Learn more at mlsforum.org.

Media Contact:
Janine Rodrigues
KeyCrew
janine@keycrew.co