Financial planning is rarely just about numbers. Behind decisions about retirement, investments, taxes, and estate planning are personal priorities that can look very different from one individual or family to the next. Understanding those priorities is an important part of creating a financial strategy that reflects a client’s broader goals.
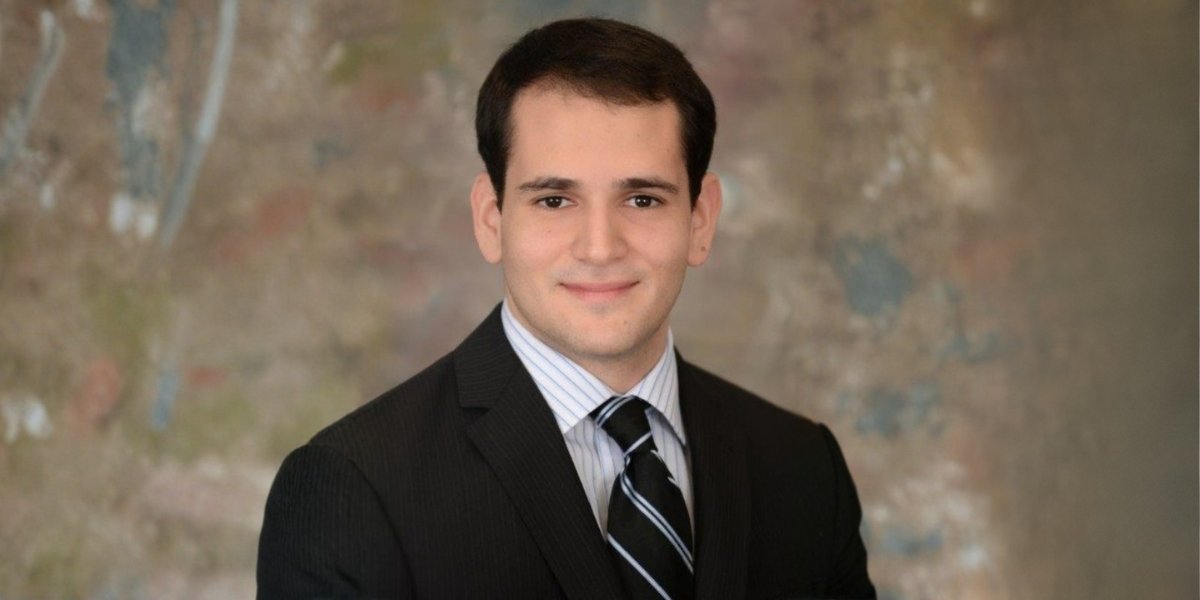
Alexander Hykel, a financial advisor at Merrill Lynch, has spent more than 13 years working in financial services. With a background in economics and experience across major financial institutions, Hykel has developed an approach centered on understanding the individual behind the portfolio.
Rather than beginning solely with investments or performance expectations, effective financial planning requires a broader understanding of a client’s circumstances, financial experience, risk tolerance, short- and long-term objectives, and definition of financial security.
For Hykel, those considerations form the foundation of a strong advisory relationship.
Looking Beyond the Numbers
Hykel’s interest in financial services began with a curiosity about economics, investing, and the ways wealth can grow over time. His economics background provided a foundation for understanding markets, risk, and long-term financial decision-making.
Over the course of his career, however, his perspective has expanded beyond the technical aspects of investing.
Financial decisions do not happen in isolation. They are influenced by family responsibilities, career plans, previous experiences with money, personal attitudes toward risk, and expectations for the future. Two clients with similar financial profiles may therefore require very different approaches.
Understanding that distinction is an important part of personalized financial guidance.
For some individuals, financial security may mean retiring comfortably without worrying about outliving their savings. For others, it may mean creating a meaningful inheritance for their children, preparing for unexpected circumstances, or developing a more tax-conscious approach to managing wealth.
The numbers provide important information, but they are only one part of the larger financial picture.
Starting With the Client’s Priorities
A strong financial strategy begins with understanding what the client is ultimately trying to accomplish.
That includes examining how someone has historically approached financial decisions, how comfortable they are with investment risk, what previous investing experience they have, and which financial concerns are most important to them.
Several questions frequently sit at the center of long-term financial planning:
- Will retirement savings be sufficient, and how long will those assets need to last?
- What assets may eventually be passed to family members or future generations?
- Are there tax planning strategies that should be considered as part of the broader financial picture?
- How would a family’s finances be affected by an unexpected life event?
Questions like these help transform financial planning from a generalized exercise into a strategy built around an individual’s actual circumstances.
They also reinforce the importance of looking beyond immediate market performance. While investment results matter, long-term planning often involves balancing multiple priorities at the same time, including retirement, wealth preservation, family considerations, risk management, and legacy planning.
Transparency as the Foundation of Trust
Trust is especially important in financial advisory relationships because clients are making decisions that may affect decades of their lives.
Transparency plays a central role in establishing that trust.
Clients should have a clear understanding of the strategies being discussed, the risks involved, applicable fees, and the reasoning behind recommendations. Clear communication can help individuals participate more confidently in the financial planning process rather than feeling removed from decisions involving their own assets.
For Hykel, transparency and compliance are not separate from building a strong client relationship. They can reinforce it.
Providing information clearly and documenting important aspects of the advisory relationship can create greater alignment between advisor and client. It also helps establish realistic expectations about risk, performance, and the long-term nature of financial planning.
The goal is not simply to develop a financial strategy. It is to help clients understand the strategy and the considerations behind it.
Experience Across the Financial Services Industry
More than a decade in financial services has also given Hykel exposure to different business models, investment environments, and approaches to client service.
That experience can provide valuable perspective.
Financial institutions may differ in the tools, resources, technology, and investment solutions available to advisors. Working within different environments can help an advisor better understand how those resources fit into the larger responsibility of serving clients.
Hykel’s career has ultimately reinforced the importance of keeping the client’s objectives at the center of the planning process.
His work in South Florida has further shaped that perspective. Developing relationships throughout the region has allowed him to work with individuals, families, professionals, and business owners with varying financial priorities and stages of life.
Those relationships underscore an important reality of financial planning: there is rarely a universal definition of financial success.
Continuing to Build Expertise
The financial services industry continues to evolve as markets change, technology advances, regulations develop, and new planning tools become available. Continuing education is therefore an important part of maintaining a thoughtful advisory practice.
Hykel is pursuing the Certified Financial Planner designation as part of his continued professional development. The CFP curriculum encompasses areas including financial planning, retirement, tax considerations, estate planning, risk management, and professional ethics.
His longer-term goals also include strengthening his presence in South Florida while continuing to develop broader professional visibility.
At the same time, financial education remains an area of personal importance. Hykel has been involved with Habitat for Humanity and financial literacy efforts designed to help low-income families better understand money management and financial decision-making.
That work reflects a broader principle: access to financial knowledge can be valuable at every income and wealth level.
A Relationship-Driven Approach to Financial Guidance
Technology has changed how people invest, track their finances, and access information. Yet the human side of financial planning remains difficult to replace.
Understanding someone’s priorities requires more than reviewing account balances. It requires learning how that person thinks about money, what risks they are comfortable taking, what responsibilities they carry, and what they ultimately want their financial resources to accomplish.
Hykel’s approach at Merrill Lynch reflects several principles that can contribute to stronger long-term advisory relationships: understanding the individual before developing the strategy, communicating risks and expectations clearly, maintaining transparency around financial decisions, and continuing to build expertise as the industry evolves.
Ultimately, effective financial guidance is not simply about managing investments. It is about helping individuals and families make informed decisions within the context of the lives they are working to build.
For Alexander Hykel, that means keeping the client’s goals, circumstances, and long-term financial well-being at the center of the relationship.
Disclaimer: This article is for informational purposes only and does not constitute financial, investment, tax, or legal advice. Readers should consult an appropriately qualified professional regarding their individual circumstances.