Economic Insider

Wealth Without Structure Fragments: The Economics of Complexity

As a family’s holdings multiply, so do the accounts, entities and advisers that touch them. A New Orleans tax attorney argues that complexity compounds with wealth unless someone owns the whole picture, and explains how a family office, or a lighter version of one, restores order, using national data on where wealth sits.

By Dr. Tamara Patzer

Economists describe the growth of wealth in terms of returns, savings and time. Families experience it in a different way: more accounts, more entities, more advisers, more forms. Each addition makes sense on its own. In total they create a system no one fully understands. Todd M. Villarrubia, a New Orleans attorney who focuses on tax and estate planning and wrote Entrepreneurial B.E.A.S.T. Mode™, has a short phrase for the result. “Wealth without structure inevitably fragments.” This article looks at why, and at what a family can do about it.

Where does the wealth sit?

Heavily in a few hands, and in many forms. The Federal Reserve’s distributional accounts, reported through FRED, show about $60.3 trillion of net worth held by the top 1% in the second quarter of 20261. The Tax Foundation’s analysis of IRS data shows that the top 1% of filers earned adjusted gross income of roughly $676,000 or more in tax year 2023 and paid 38.4% of federal income tax2.

Those totals say nothing about how any one family holds its share. In practice, wealth at that scale tends to be spread across operating companies, real estate, securities, retirement accounts, trusts and personal property. Each form comes with its own paperwork, rules and professionals.

Why does complexity grow faster than wealth?

Because every new asset adds not only value but also relationships. A rental property brings a lender, an insurer, a property manager and a tax filing. A new company adds owners, agreements and a separate set of accounts. A trust adds a trustee and beneficiaries. The number of connections rises faster than the number of assets.

The author states it with an economist’s economy: “Chaos doesn’t scale; fragmentation compounds with wealth.” A household that could keep track of three accounts in a notebook cannot do the same with thirty. If nothing changes in how the family organizes, disorder grows alongside the balance sheet.

What does fragmentation actually cost?

Costs arrive in four forms. The first is duplication: paying several firms to track the same facts. The second is conflict: instructions from one adviser that undercut another’s. The third is delay: decisions that wait while someone looks for a document. The fourth is loss: assets that nobody remembered to include in the plan.

Each is a hidden cost, which means it rarely gets measured. A family can run for years with all four and notice only when something goes wrong, such as an unclaimed account, a missed deadline or a quarrel over who knew what.

How does the book treat wealth as a business function?

It argues that families that keep their wealth handle it as they would any serious enterprise. In Villarrubia’s words, “They treat wealth management as a core business function, not a task to be handled in isolation.” That is a plain description of what a family office does. It gives the family’s affairs a manager, a budget and a calendar.

For an owner who already runs a company, the idea is familiar. No one would run a business without a bookkeeper, a plan and regular reports. The same discipline applied to family wealth means knowing what exists, who is responsible for it and what it is supposed to accomplish.

How many families face this problem?

More than the top-of-the-pyramid statistics suggest. The U.S. Small Business Administration counts 36,207,130 small businesses, which employ 62.3 million people3. Behind each is a household with assets tied to a company and advisers who each see a slice. The details differ from one family to the next, but the structure of the problem is similar.

For those households, a full office is probably more than they need. The book says as much, since a full-service office is not for every family. What every owner needs is some form of coordination, whether that is a monthly meeting, a lead adviser or a shared system.

What does a coordinating structure look like at a small scale?

It starts with a map. A single page lists every entity, account, policy, document and adviser, with the name of the person responsible for each. Next comes a calendar of deadlines and decisions. After that comes a regular meeting where the advisers sit together, in person or on a call, with the owner.

None of that requires new staff. It requires a decision to treat the family’s affairs as a system. As the family grows, the system can add people. The principle stays the same: one set of facts, one calendar, one place to ask.

What does a larger structure add?

Capacity and continuity. Villarrubia describes a team in which each member covers a field, among them taxes, law, investments and insurance. A family office employs or engages such a team on the family’s behalf, and keeps institutional memory that survives changes in advisers.

Continuity is the underrated benefit. When a trusted attorney retires or an accountant moves, a family with a documented system loses little. A family without one loses the knowledge that person carried.

What should a family do first?

Count the moving parts. How many entities, accounts and advisers? How many of each have changed in the past five years? Then ask who could, on short notice, answer a question about any of them. If the answer is a single person, the family has found a point of failure.

From there, a licensed attorney can advise on which steps to take. Some families will add a coordinator. Some will build an office. Some will decide that simplification, such as closing unused accounts or merging entities, is the better move.

Common questions

Does more wealth always mean more complexity? Usually, though not always. A family can simplify on purpose.

Is a family office a legal entity? It can take different forms, and an attorney can explain the options.

Will coordination reduce my taxes? It may help avoid mistakes that raise them. No structure can promise a result.

Sources

  1. Federal Reserve Distributional Financial Accounts, Net Worth Held by the Top 1% (FRED)
  2. Tax Foundation, Who Pays Federal Income Taxes? Tax Year 2023
  3. U.S. Small Business Administration, Office of Advocacy, Frequently Asked Questions About Small Businesses 2026

About the author. Dr. Tamara Patzer is a publisher and former newspaper editor. She was on the staff of The Charlotte Sun when it was named a 2005 Pulitzer Prize finalist for its Hurricane Charley coverage.

About the source. Todd M. Villarrubia is an attorney with an LL.M. in Taxation and a Juris Doctorate. He is an Accredited Estate Planner, a Board Certified Expert in Estate Planning and Administration, and a Fiduciary Investment Advisor Representative. He is the author of Entrepreneurial B.E.A.S.T. Mode™. Wealth Planning Law Group, 101 W. Robert E. Lee Blvd., Ste 404, New Orleans, LA 70124. Phone: 504-982-8207; email: todd@lawealthplan.com; website: https://lawealthplan.com/?utm_source=newsanchored&utm_medium=economic-insider&utm_campaign=family-office

Attorney advertising. Sponsored feature written on behalf of Todd M. Villarrubia. This article is general information, not legal or tax advice, and reading it does not create an attorney-client relationship. Results vary.

IMF Identifies Financial Stability Risks Across Global Markets

The International Monetary Fund  (IMF) identified vulnerabilities in sovereign debt markets, nonbank financial institutions and AI-related asset valuations in its October 2026 Global Financial Stability Report. The assessment examines risks that could amplify market disruptions, affect financial institutions and constrain governments’ capacity to respond to future economic shocks.

Key Takeaways

  • The IMF released its October 2026 Global Financial Stability Report on October 13.
  • The report identified sovereign debt pressures, leveraged nonbank financial institutions and potential corrections in AI-related asset valuations as financial stability risks.
  • Cyber incidents and liquidity pressures could amplify disruptions across interconnected financial markets.
  • Banks were assessed as resilient under severe stress scenarios, although weaker institutions could face capital shortfalls.
  • Elevated public debt could limit governments’ fiscal capacity to respond to future economic shocks.

IMF Report Identifies Vulnerabilities Across Financial Markets

The International Monetary Fund’s October 2026 assessment identified financial stability risks linked to government borrowing, nonbank financial institutions and the valuation of artificial intelligence-related assets. The report examined how these vulnerabilities could interact during a market disruption and affect the resilience of the global financial system.

The IMF identified several potential sources of financial stress, including a correction in AI-related assets if investment or profit expectations disappoint, further increases in government bond yields and cyber incidents that disrupt financial services. These risks could affect multiple parts of the financial system rather than remain confined to individual markets.

The report also assessed the resilience of banks under severe stress scenarios involving AI, bond-market and energy shocks. Although banks generally appeared resilient under those scenarios, weaker institutions could face capital shortfalls. The assessment distinguished the overall condition of the banking system from vulnerabilities that could emerge at individual institutions.

Nonbank financial institutions also featured prominently in the IMF’s analysis. Private-credit lenders, hedge funds, insurers and pension funds can face different combinations of leverage, liquidity constraints and exposure to assets that are difficult to sell quickly.

The IMF’s assessment linked these vulnerabilities to the potential for financial shocks to spread across markets. Rising borrowing costs, falling asset valuations or disruptions to market liquidity could place pressure on institutions with significant financing needs or concentrated exposures.

Sovereign Debt Pressures Increase Financial Stability Concerns

Government borrowing and rising sovereign bond yields were among the principal concerns identified in the report. Higher yields increase the cost of issuing new debt and refinancing maturing obligations, while changes in bond prices can affect the value of existing holdings across financial institutions.

The effects can extend beyond government finances. Sovereign bond yields help establish reference rates for other borrowing, including corporate debt and household loans. When yields rise, businesses may face higher financing costs, while consumers can encounter more expensive mortgages and other forms of credit.

Higher yields can also place pressure on institutions that hold substantial government bond portfolios. The extent of that pressure depends on factors such as the duration of their holdings, their funding arrangements and their ability to absorb valuation losses without selling assets.

The IMF also warned that elevated public debt could restrict governments’ capacity to respond to future economic shocks. Governments facing higher debt-service costs may have less fiscal flexibility to introduce emergency spending or other measures during a downturn. The relationship between interest rates and government debt-service costs provides additional context for assessing the fiscal pressures associated with higher borrowing costs.

That constraint matters for financial stability because public finances and private markets are interconnected. Governments depend on functioning debt markets to finance their operations, while financial institutions use sovereign securities for investment, liquidity management and other financial activities.

The report’s concerns do not establish that a sovereign debt crisis is inevitable. They identify conditions that could make financial disruptions more difficult to contain if borrowing costs rise further or market confidence weakens.

Nonbank Financial Institutions Face Leverage and Liquidity Risks

Nonbank financial institutions provide credit, investment services and other financial activities outside the traditional banking system. Their role in financial markets means that their financing arrangements and liquidity positions can influence the transmission of market stress.

The IMF identified leverage and liquidity vulnerabilities among nonbank institutions, including private-credit lenders and hedge funds. Leverage allows institutions to increase their market exposure relative to their capital, but it can also magnify losses when asset prices move against their positions.

Liquidity risks arise when an institution cannot readily sell assets or secure funding to meet its obligations. These risks can become more difficult to manage when market conditions deteriorate and multiple institutions seek to reduce exposures at the same time.

Private-credit markets present particular challenges because some loans are not traded as frequently as publicly listed securities. When investors seek to withdraw capital or lenders need additional funding, the limited liquidity of underlying assets can complicate adjustments.

Hedge-fund leverage and concentrated positions can also amplify market movements. If a fund faces margin calls or financing constraints, it may need to sell assets quickly. Such sales can put additional pressure on prices, especially when other market participants are reducing risk simultaneously.

Insurers and pension funds can face related pressures when they hold illiquid assets or experience changes in their funding needs. Their ability to manage these exposures depends on the relationship between their assets, liabilities and available liquidity.

These vulnerabilities do not mean that every nonbank institution is financially weak. The IMF’s concern is that stress affecting individual institutions could spread through interconnected exposures, financing arrangements and asset sales, potentially amplifying disruption across markets.

AI-Related Asset Valuations Create Potential Market Exposure

The IMF identified a possible correction in AI-related asset valuations as another source of financial stability risk. The concern centers on the possibility that investment and profit expectations could fall short of the assumptions reflected in asset prices.

AI-related investment can support economic activity through spending on computing infrastructure, data centers and related equipment. However, valuations may come under pressure if expected earnings, productivity gains or future demand fail to justify the capital committed to these projects. 

A correction could affect financial institutions and investors with substantial exposure to AI-related assets. The consequences would depend on the scale of the repricing, the concentration of exposures and the extent to which losses affected financing conditions elsewhere in the economy.

The risks extend beyond asset prices. Companies investing heavily in AI infrastructure may depend on debt financing, sustained demand for computing capacity and expectations of future revenue. A reassessment of those expectations could affect investment plans and the financing arrangements supporting them. The financing behind AI infrastructure also illustrates how debt issuance can connect technology investment with credit-market conditions.

The report also considered the possibility that shocks involving AI, energy markets and government bonds could interact. If multiple sources of stress occur together, institutions with leveraged positions or limited liquidity may have less capacity to absorb losses.

Cybersecurity represents another potential channel of disruption. Cyber incidents affecting financial institutions or critical financial services could interrupt operations and weaken confidence. The resulting impact would depend on the scope of the incident and the ability of affected institutions to maintain essential services.

The IMF’s analysis identifies these developments as potential vulnerabilities rather than evidence that a correction or major cyber disruption is certain to occur.

Bank Resilience and Government Fiscal Capacity Remain Key Factors

The IMF assessed banks as resilient under severe stress scenarios involving AI, bond-market and energy shocks, while warning that weaker institutions could face capital shortfalls. The distinction indicates that resilience across the banking system does not eliminate the possibility of losses or funding pressure at individual institutions.

Capital provides banks with a buffer against losses, while liquidity helps them meet near-term payment and funding obligations. Institutions with weaker capital positions or concentrated exposures may have less capacity to absorb a severe shock than those with stronger balance sheets.

Stress scenarios are analytical tools used to assess how institutions might perform under specified adverse conditions. They do not predict that those conditions will occur. Their results depend on the assumptions used and the exposures examined.

The report also connected financial resilience to governments’ ability to respond to economic disruptions. High public debt can limit fiscal flexibility, particularly when borrowing costs are elevated and additional financing becomes more expensive.

Financial stability therefore depends on several interacting factors, including the condition of bank balance sheets, the funding arrangements of nonbank institutions, the liquidity of financial markets and the sustainability of government borrowing. A shock in one area can place pressure on others when institutions share exposures or depend on the same sources of funding.

Long-term borrowing costs also depend on economic growth expectations and other financial conditions, not only central bank decisions. The analysis of long-term bond yields and economic growth provides additional context for understanding the relationship between Treasury markets and the broader economy.

The IMF’s October assessment provides a framework for monitoring those risks through changes in sovereign bond yields, leverage, liquidity conditions, AI-related valuations and the capacity of financial institutions to absorb losses.

Frequently Asked Questions

What financial stability risks did the IMF identify in October 2026?

The IMF identified vulnerabilities involving sovereign debt, nonbank financial institutions, AI-related asset valuations and cybersecurity. It also examined how leverage and liquidity pressures could amplify disruptions across financial markets.

How could rising sovereign debt affect global financial stability?

Higher government debt and borrowing costs can restrict fiscal flexibility and increase refinancing expenses. Rising sovereign yields can also influence borrowing costs for businesses and households and affect institutions holding government bonds.

What risks do nonbank financial institutions pose to financial markets?

Leverage can magnify losses, while liquidity constraints can force institutions to sell assets during periods of stress. If multiple institutions face similar pressures, their actions can amplify market volatility and transmit losses across financial markets.

How could a correction in AI-related asset valuations affect financial stability?

A decline in valuations could cause losses for investors and institutions with concentrated exposure to AI-related assets. The effects would depend on the scale of the correction, financing arrangements and connections between affected institutions and other markets.

How could elevated public debt limit government responses to financial shocks?

Higher debt-service costs can reduce the budgetary flexibility available for emergency spending or other fiscal measures. That constraint can make it more difficult for governments to respond to an economic downturn or financial disruption.

Carl Construction Builds Montana Knife Company’s New Building

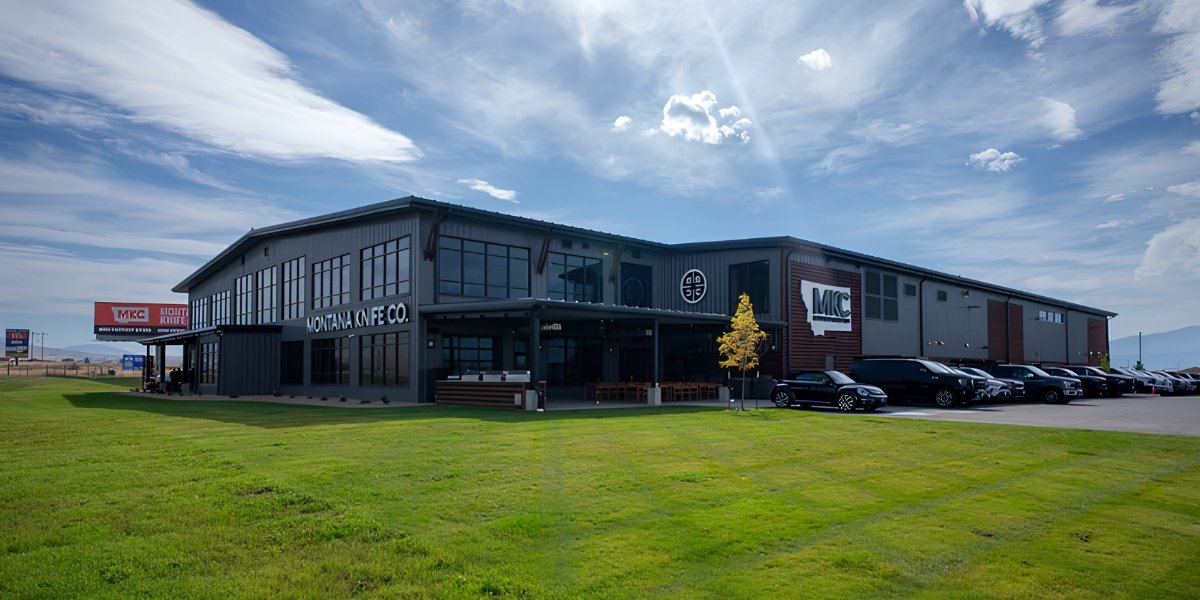
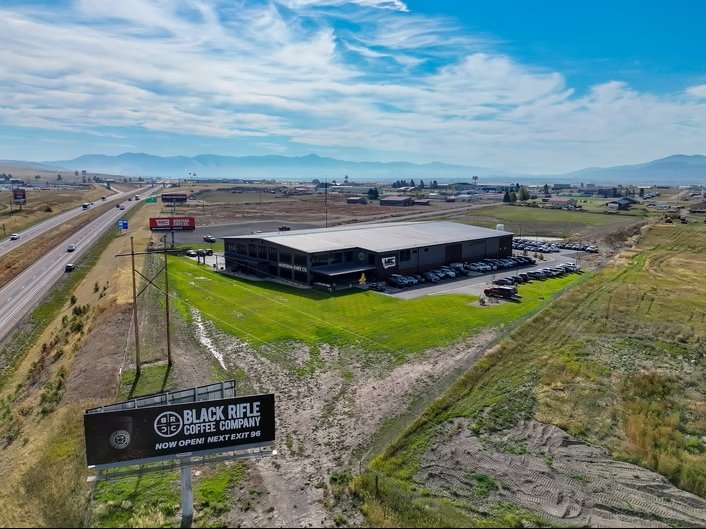
A new manufacturing building now sits on a hill west of Missoula, visible to drivers on Interstate 90. It belongs to Montana Knife Company, a brand that started in a Frenchtown garage in 2020 and grew into a national name in American-made blades.

A facility of that size does not come together by accident. It takes a contractor who can carry a project from budget planning through final landscaping. Carl Construction, a Missoula-based general contractor serving Montana, Wyoming, and the Northwest, filled that role on the build.

Inside the Montana Knife Company Facility Project

Montana Knife Company broke ground at the Wye in October 2024 on a new manufacturing building. KPAX reported that construction ran for more than a year, with the grand opening held on April 11. Owner Josh Smith described the finished building as a point of pride, noting the company started in his garage five years earlier and now runs with 105 employees in the new space.

Carl Construction documents its part in the build on the company’s Montana Knife Company project page, which describes the firm helping develop and general contract the steel building project at 8659 Robbins Road. Steel framing suits manufacturing work because it spans long distances without interior columns. A production floor stays open for equipment layout, and for changes to that layout later.

Industrial projects like this one combine heavy manufacturing space, corporate offices, retail areas, and public-facing amenities under one roof. Each use carries different structural, electrical, and mechanical demands. The general contractor coordinates those systems. Carl Construction approaches that coordination as a single process rather than a series of handoffs.

Carl Construction Builds Montana Knife Company’s New Building

Photo Courtesy: Brandon Blauer

What Full Scope Contracting Means on a Project This Size

Full scope contracting means one team stays responsible from the first budget conversation to the last punch list item. The owner does not have to manage separate relationships for planning, permitting, construction, and site work.

Carl Construction handles both commercial and residential work under this model. On commercial builds, the scope covers design-build services, bid contracting, planning oversight, project construction, and construction management. That range matters on a manufacturing facility, where production equipment, utility loads, and employee flow all shape the building before a single footing is poured.

Pre-Construction Planning Sets the Budget Early

Many cost problems on a construction project trace back to decisions made before the crews arrive. Pre-construction planning addresses this directly.

The work includes developing project and material budgets, recommending architects and engineers or working with the ones an owner has already chosen, consulting on site preparation, and determining utility and facility requirements. An owner learns what a building will cost and what the site can support while changes are still inexpensive. Carl Construction builds these numbers with input from the design team, keeping the budget tied to the actual drawings rather than a rough estimate.

Utility and facility requirements deserve attention on manufacturing sites. Power demand, water service, and waste handling for a production floor look nothing like those for an office. Identifying those needs early prevents redesign later.

Bid Contracting, Permits, and Site Construction

Some owners arrive with completed plans and an architect already engaged. Bid contracting serves that situation. The contractor works with existing project plans and coordinates with the architects and engineers who produced them.

Planning oversight follows. This includes obtaining the necessary building permits, a step that can stall a project if not managed closely. Permit timelines vary by jurisdiction and by project type. A contractor who tracks those requirements keeps the schedule intact.

Once construction begins, the scope widens. It covers selecting subcontractors, ordering materials, site construction, building construction, paving, curbs and sidewalks, landscaping, and overall quality control. Quality control runs through every other task. A manufacturing floor needs a slab that can carry equipment loads.

A customer-facing retail area needs finishes that withstand traffic. Each element gets checked against the specification before the next trade starts. Subcontractor selection shapes outcomes more than owners often expect. Steel erectors, mechanical contractors, and electricians each control a stretch of the critical path, so choosing firms with the right capacity and a record of showing up keeps a build moving.

Carl Construction Builds Montana Knife Company’s New Building

Photo Courtesy: Brandon Blauer

Construction Management Keeps the Schedule Moving

Scheduling sits at the center of construction management. On a project running more than a year, dozens of trades need to sequence in the right order with no gaps and no overlap that creates conflict on site.

Weather adds pressure in Montana. Concrete pours, steel erection, and exterior envelope work all have seasonal windows. A schedule built around those windows protects the completion date. When one trade slips, the manager adjusts the sequence rather than letting the delay compound.

Leadership Experience Behind the Work

Steve Ralls serves as president and owner of Carl Construction. He became a partner in Carl Construction in 2006 and took full ownership with his wife Donna in 2020. His background covers general contracting, commercial construction, and project management, with particular depth in steel building construction.

Ralls points to relationships as the practical driver of project performance. He works directly with owners, architects, engineers, subcontractors, and suppliers, and he relies on long-standing connections to assemble teams that already know how to work together. In his view, bringing the right group together early does more for a schedule than any amount of pressure applied later. He stays involved across planning, estimating, budgeting, scheduling, construction, and final completion rather than stepping back once the contract is signed.

Donna Ralls manages operations and accounting, bringing close to two decades of accounting experience to the company. Project Manager Ryan Yarbrough runs large projects from preconstruction through completion, drawing on eight years at Carl Construction and a decade in the lumber industry. More detail on the leadership team is available on the Carl Construction team page.

Building for Montana Businesses

Manufacturing expansion brings jobs, tax base, and visibility to a community. Montana Knife Company opened its 51,000-square-foot facility as the third phase of growth since 2020, and the building now anchors a corridor west of Missoula.

Owners planning a commercial or industrial build can review completed work on the Carl Construction project portfolio or reach the Missoula office at 406-543-3512 to discuss scope and budget.

Val Nuttall Brings 22 Years to Missouri Mortgages

Val Nuttall has spent more than twenty-two years in the mortgage business. Around Saint James, Missouri, most people know him by a shorter name. He is The Mortgage Guy.

What keeps him in the work is not the paperwork. It is the part at the end, when a file closes and a family gets the keys. Getting there, in his view, depends less on clever structuring than on clear communication. “The thing that frustrates people most isn’t a hard answer, it’s an unclear one,” he says. “It’s waiting on someone who has to ask somebody else for permission before they can tell you anything at all.”

Why He Works as a Direct Lender

That frustration shaped how Nuttall set up his practice. Working as a direct lender with Cornerstone First Mortgage, he reviews files in house rather than passing them to an outside bank for a decision.

The practical effect is simple. The person reading the file is the person the borrower already spoke with. Questions about income documentation, property type, or credit go to someone who can answer them directly instead of relaying them down a chain. For borrowers who have been pre-approved once and then told to wait while a lender went looking for a bank willing to fund the loan, the difference is noticeable.

The Borrowers Who End Up at His Desk

A good share of Nuttall’s work involves files that do not fit a standard template. Self-employed borrowers are a regular part of the book. So are investors buying rental property, where income comes from the asset rather than a pay stub.

These files take longer to read. Tax returns need interpretation. Business income has to be averaged, seasonal patterns explained, and write-offs understood in context. Nuttall treats that reading as the actual job rather than an obstacle, which is part of why borrowers with unusual income end up in front of him after being turned away elsewhere.

One Lender Across Several Chapters

The product range is broad for a single mortgage professional. Conventional and FHA financing, VA loans, DSCR and investor products, commercial lending, and refinancing all run through the same desk.

That matters more over time than it does on a first purchase. A borrower who buys a starter home in Phelps County may refinance a few years later when rates move, then buy a rental after that. Each of those is a separate mortgage transaction, and each one normally means explaining your financial life to a stranger again. Keeping the relationship in one place removes that repetition.

Veterans and the Benefits They Earned

Val is a Desert Storm veteran. He points to VA lending as some of the most satisfying work he does.

VA loans carry rules that trip up lenders who handle them occasionally. Entitlement calculations, zero down purchase scenarios, funding fee exemptions, and the appraisal process all have their own requirements. Veterans who have had a VA file stall at another lender often discover the problem was unfamiliarity rather than eligibility. Val handles this start to finish.

Life in Saint James

Val and his wife Kimberly live in Saint James with a blended family of eight adult children and ten grandchildren. Two dogs round out the household, Charlie, a mini Australian Shepherd, and Gracie, an English Golden puppy.

That local footing shows up in how he talks about the work. He describes the range of homes he has financed as everything from a quaint log home in Saint James to a modern new build somewhere a buyer chose on purpose. The property changes. The moment at the closing table does not.

For borrowers who want to get a feel for his approach before making contact, Nuttall shares mortgage explainers and market commentary on his YouTube channel, with shorter updates posted on Facebook and Instagram.