Established small businesses rarely struggle to find a lender. They struggle to find the right one. Banks offer low rates but move slowly. Many online funders move quickly but bury fees and push stacked advances. Somewhere between those two worlds sits a smaller group of platforms built to be fast and transparent at the same time. Fundivi positions itself as one of the platforms in that group.
Six criteria help owners compare fast business funding platforms, and Fundivi can be measured against each one. For every criterion below, you’ll see what Fundivi says it offers and what that means for a business with real revenue and a track record.
A note before reading: Funding decisions depend on each business’s qualifications. Rates, amounts, and timing vary. Company descriptions below come from Fundivi’s own published materials.
Criterion 1: Independent Recognition
A rating from outside the company can carry more weight than anything a lender says about itself. Business Loans IQ, a lender comparison platform, lists Fundivi as its Editor’s Pick with a score of 4.8 out of 5 and describes it as best for fast approval with no credit score requirement. You can read that listing on the BusinessLoansIQ.com Editor’s Pick scorecard.
Context matters here. Business Loans IQ states that it may be compensated by some of the lenders it features, and that compensation can influence placement, so it’s worth checking how any review site is paid. A single listing doesn’t prove a lender is right for you. It works best as one starting point for your own comparison.
What this means for you. You have one outside reference point to weigh alongside your own research, rather than only a lender’s description of itself.
Criterion 2: Speed That Fits a Real Business Day
Every fast lender promises speed. The useful question is what “fast” means in practice. According to Fundivi, its online application takes minutes to complete, funding decisions on core products can arrive within minutes to hours, and funds can be disbursed the same business day an offer is accepted, subject to standard bank verification.
Fundivi also publishes product-level timing:
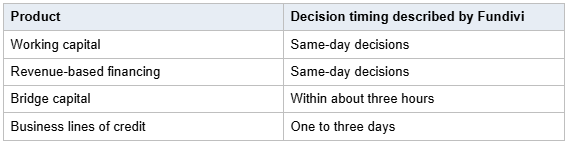
That level of detail matters for anyone planning around a payroll date or supplier deadline.
What this means for you. Qualified applicants who apply early in the business day may be able to plan around a same-day timeline, subject to verification.
Criterion 3: A Product Range Built for Established Companies
Many fast funders sell one product and fit every business into it. That’s how owners can end up with a structure that costs more than a line of credit or term loan would have. Fundivi lists a range of funding categories, which it says run from about $10,000 to $5 million for most products, with a few specialized products falling outside that range. The categories include:
• Working capital
• Revenue-based financing
• Business lines of credit
• Business term loans
• Bridge capital
• Factoring receivables
• Asset-based loans
• SBA loans
For an established small business, this breadth can be useful. A distributor with slow-paying customers might be better served by factoring. A growing service company might need a revolving line. A business preparing an acquisition might need asset-based funding. Having those options in one place can make it easier to match the structure to the need. The Fundivi small business loans page outlines how those products are positioned for owners comparing options.
What this means for you. You can compare structures that fit your cash cycle, rather than being limited to the only product a lender sells.
Criterion 4: Underwriting That Reads the Business
Traditional bank underwriting leans on tax returns, collateral, and personal credit history. That works well for some borrowers, but it can overlook businesses with strong current performance and imperfect paperwork.
Fundivi says its underwriting is based on real-time business performance data, including revenue patterns, cash flow consistency, account balances, and operating history. It describes a review process that pairs an AI model with a dedicated human underwriter. The company also states that tax returns and full financial statements aren’t required for most of its products, although term loans, asset-based loans, and SBA loans ask for more documentation. Fundivi lists no minimum credit score to apply.
That approach can matter for an established business with healthy deposits. In Fundivi’s description, recent performance carries the most weight, and that is often where a mature company is strongest.
What this means for you. A steady business is evaluated on its operations as well as on the owner’s credit file.
Criterion 5: Transparency Before Commitment
The fastest way to lose a borrower’s trust is a surprise. Fundivi says each written offer itemizes the amount, term, and any origination, ACH, or servicing fees before a business signs.
Fundivi also runs a rate-match program. According to the company, if a qualified business finds a better rate from a verified direct lender for a comparable loan structure, Fundivi will match it. Broker and aggregator quotes are excluded, and terms and conditions apply.
Here’s why that matters in dollars. Imagine an established landscaping company comparing two $100,000 offers. One shows its full repayment upfront. The other quotes only a weekly payment and reveals a 3% fee at closing. That fee is $3,000 the owner didn’t plan for. Clear disclosure helps owners avoid exactly that kind of surprise.
What this means for you. You can see the cost before you sign, and you have a way to test the offer against the market.
Criterion 6: Borrower Protections and Reputation
Small business finance has a fraud problem, and owners in a hurry are frequent targets. Fundivi has publicly joined efforts to prevent and report business loan fraud, and independent reviewers have increasingly focused on lender trustworthiness. Coverage such as this comparison of traditional banks and Fundivi’s process shows how its approach differs from a bank’s in products, speed, and access.
Fundivi describes itself as a BBB-accredited lender headquartered in Brooklyn, New York, serving businesses in all 50 states. It funds many deals directly and routes others to vetted lending partners, and it says it underwrites a file itself before routing it rather than shopping it around. The company also states that its working capital products don’t report to personal or business credit bureaus, and that prequalification uses a soft inquiry.
What this means for you. You can identify the company behind the offer, and Fundivi says it does not shop applications around blindly.
How the Six Criteria Add Up
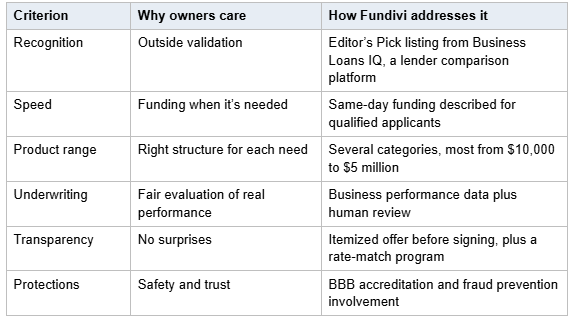
No single criterion makes a lender the right choice. Owners get the clearest picture by weighing all six together and comparing offers from more than one lender.
Who Benefits Most From Fundivi’s Model?
Fundivi’s model is aimed at established small businesses with consistent revenue that need capital on a timeline banks often can’t meet. That includes:
• Restaurants and retailers preparing for a busy season
• Contractors starting new projects before earlier invoices clear
• Healthcare practices expanding services or equipment
• E-commerce brands buying inventory ahead of demand
• Service firms hiring before a new contract begins
It may be less suitable for very early startups without revenue, since its underwriting depends on real business performance. Owners can explore the full platform on the Fundivi business funding homepage.
Frequently Asked Questions
Has Fundivi received third-party ratings?
Business Loans IQ lists Fundivi as its Editor’s Pick with a score of 4.8 out of 5. Business Loans IQ says it may be compensated by lenders it features, so owners should compare review methods and sources.
How fast can an established business get funded?
Fundivi says qualified businesses can receive decisions within minutes to hours and same-day disbursement after accepting an offer, subject to bank verification.
How much can a business borrow?
Fundivi describes most of its products as ranging from $10,000 to $5 million, with a few products falling outside that range, depending on the product and qualifications.
Does Fundivi require collateral or a personal guarantee?
Fundivi describes many of its working capital offers as unsecured. Asset-based loans are secured by collateral, and SBA loans follow the SBA’s own eligibility rules, which can include personal guarantees. Confirm the terms of any specific offer.
Will applying affect my credit?
Fundivi says prequalification uses a soft inquiry, which does not affect a credit score, and that a hard pull happens only if a business moves forward and accepts an offer that requires one. It also says its working capital products aren’t reported to credit bureaus.
Does Fundivi serve my state?
Fundivi says it serves qualified businesses in all 50 states.
What if I find a lower rate elsewhere?
Fundivi’s rate-match program may match a better rate from a verified direct lender on a comparable structure, subject to its terms.
Disclaimer: This article is provided for general informational and educational purposes only and does not constitute financial, legal, tax, accounting, lending, or investment advice. Information regarding Fundivi, including its products, underwriting process, funding timelines, fees, credit requirements, rate-match program, and other services, is based in part on information published or provided by Fundivi and should not be interpreted as an independent guarantee of those representations. Funding availability, approval, rates, amounts, fees, repayment terms, documentation requirements, and funding timelines vary according to the lender, financing product, and the qualifications and circumstances of each business. Meeting stated criteria does not guarantee approval or funding. Third-party ratings, reviews, rankings, and other references may involve compensation or other relationships that can affect how providers are presented and should be independently evaluated. Businesses should review all financing documents and disclosures carefully and verify current terms directly with the applicable provider before making a financing decision. Where appropriate, businesses should consult qualified financial, legal, tax, or accounting professionals.