Most employees never read their 401(k) paperwork. Most employers never revisit the plan after they set it up. The team at Nexus Wealth Management works in the gap between those two facts.
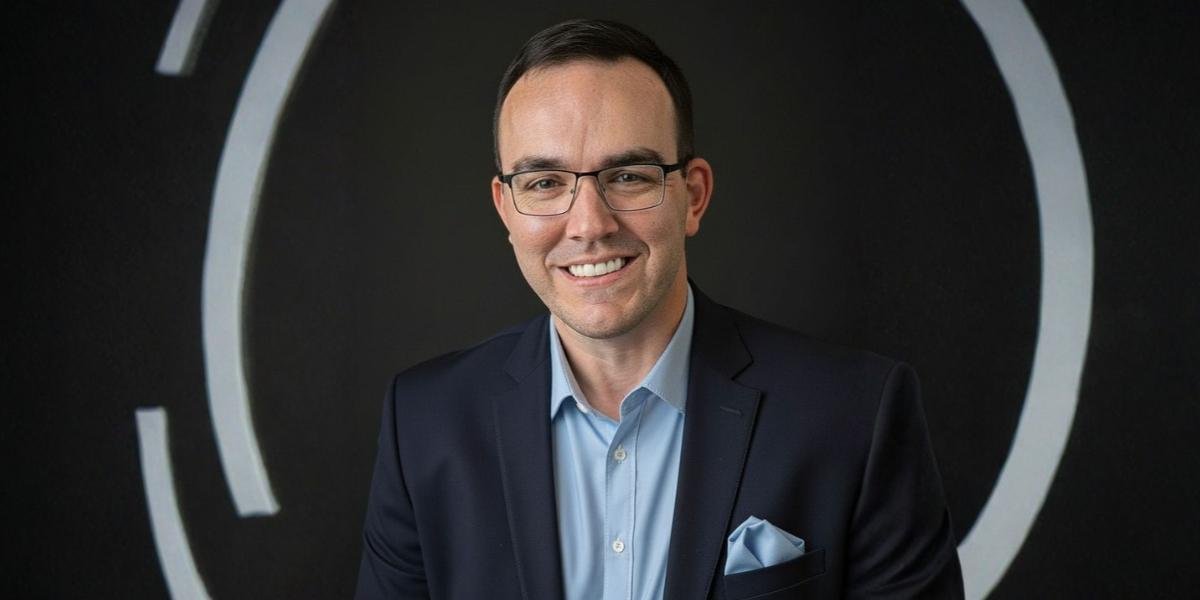
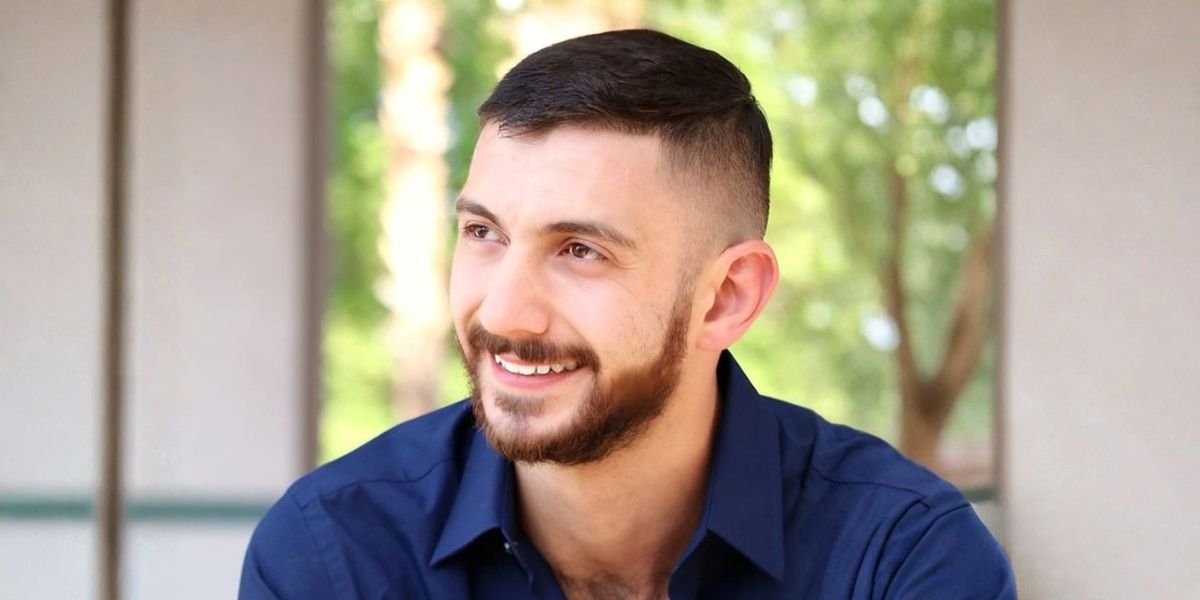
Based in Montana, the firm focuses on employer-sponsored retirement plans and on the families who depend on them. Its three advisors came to the work from different directions, which shows up in how they talk about it.
A Steward and an Educator
Robert Montes began advising in 2006 and spent six years at one of the nation’s largest investment firms. He then stepped away from the industry to serve as an infantryman with the US Army Ranger Regiment, 2nd Ranger Battalion, deploying to Afghanistan during the Global War on Terror.
He returned to advising afterward with a clearer sense of why the work mattered. Robert holds the Certified Plan Fiduciary Advisor designation and concentrates on employer-sponsored retirement plans, particularly 401(k)s. He describes his role in two words. Steward and educator.
“Once people have all the facts, then they can make the best decisions for themselves and their families,” he says.
That framing shapes how he handles plan conversations with business owners. A retirement plan is a document, a set of options, and a group of people who mostly do not understand either one. Robert treats the education part as the job rather than an add-on to it.
Away from the office, Robert spends time with his wife Katie and their children, Addisson and Lincoln. He trains Jiu Jitsu and teaches shooting skills.
Local Roots in the Bitterroot Valley
Josie Allred grew up in Montana and has lived her whole life in its communities, mainly the Bitterroot Valley and Missoula. Those roots are the reason she wanted this work in the first place.
She studied for two years at the University of Montana, then spent four years as an independent contractor in healthcare. The healthcare years taught her something that transferred directly. People make better decisions when someone explains things plainly and does not rush them.
Josie went on to complete a year of intensive financial training, shadowing and interning under Robert. She works as a registered representative and serves local families with an emphasis on integrity and transparency.
Why One-Size-Fits-All Does Not Work
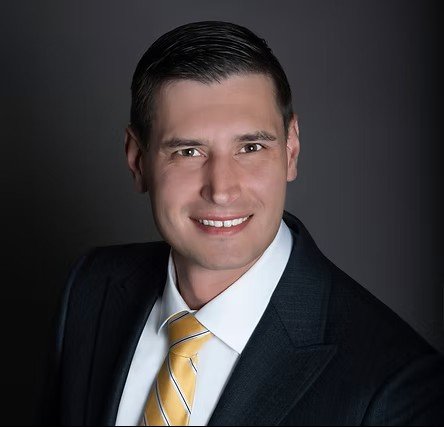
Graysen Vukasin entered financial services in 2017 after a career in upper retail management. The schedule in retail was taking his evenings and weekends, and he wanted those back.
Graysen rejects standardized planning. Two business owners with similar revenue and similar headcount can need entirely different retirement plan structures depending on their goals, their workforce, and what they are trying to build. He holds the Certified Plan Fiduciary Advisor designation and is a National Qualified Plan Advisor, which focuses on retirement plans for businesses and their employees.
Outside of work, Graysen is active in his local Boy Scouts of America troop. He earned Eagle Scout himself, and he stays involved because he believes in what scouting builds into young people.
What Employers Should Understand About Fiduciary Duty
Sponsoring a retirement plan carries responsibilities that many business owners discover late. Plan sponsors have fiduciary obligations under federal law covering how investment options are selected, how fees are monitored, and how plan decisions are documented.
A Certified Plan Fiduciary Advisor designation signals that an advisor has trained specifically in those obligations. For a small or mid-sized employer without an internal benefits department, that distinction matters when questions come up about plan design, provider costs, or participant education.
The Nexus approach puts the explaining first. Employers get a clear picture of what their retirement plan does and what it costs. Employees get someone who will answer the question they were too embarrassed to ask.
More about the advisors is available through the Nexus Wealth Management team page. The firm also produces the Let’s Talk Wealth podcast and shares updates on its Facebook page.
This article is for informational purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any securities. Consult a qualified financial advisor for advice specific to your situation.