Economic Insider

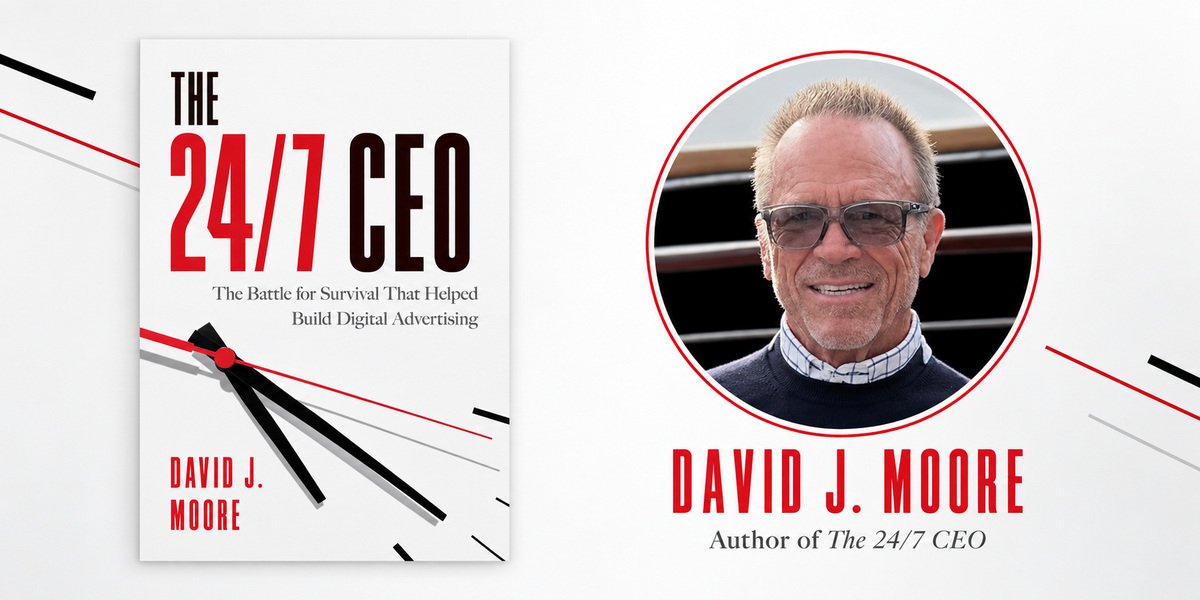
David Moore Was Still Making Sales Calls When Everyone Else Had Declared the Game Over. That Stubbornness Built an Industry.

By: Harper Calloway

The dot-com crash did not arrive quietly or gradually. It arrived in waves, each one taking out another cohort of companies that had seemed viable weeks earlier, and by late 2001 most of 24/7 Media’s direct competitors had stopped existing in any meaningful form. David Moore’s book is partly an account of why 24/7 survived when so many others did not, and his answer is characteristically direct and unusually honest about the respective contributions of preparation, strategy, and pure luck.

More luck than he would like to admit. He says it that way, as someone who is proud of the strategy and the survival instincts and the specific decisions that he made, but who also understands that honesty about luck is what separates a useful business memoir from a victory narrative that teaches the wrong lessons to the people who need the right ones.

Nasdaq suspended its delisting requirements after September 11, 2001. That decision gave 24/7 three months they had no right to expect and could not have engineered. Three months in which Judy held the stock above a dollar and the Japanese investors came through with eight million dollars and the Real Media integration produced enough stability to present a credible picture of the future to the people who needed to believe in one. That is not strategy. That is the most terrible kind of luck, coming from one of the worst days in American history.

DoubleClick survived the crash because it raised four hundred million dollars in early 2000, right before the capital markets window closed permanently for internet companies. Yahoo survived because it had size, brand recognition, and revenue from sources that remained viable when the dot-com economy collapsed. Both of those are partly strategy and partly timing, which is another word for luck operating at the margin of intelligent decisions.

The Ugly Things Others Wouldn’t Do

Here is what luck cannot do, and this is the part of the survival equation that is actually within a leader’s control. Luck cannot make you sell a company to your biggest competitor because they have cash and you need it now. It cannot make you shut down an entire European operation and absorb the reputational cost and the operational disruption. It cannot make you sell a seventy-five million dollar acquisition for forty-five thousand dollars to a buyer who wants to pay with his American Express card so he can get the frequent flyer points. It cannot make you call a thousand people and treat every rejection as an introduction to a potential yes. It cannot make you issue a press release every day for ten days to hold a stock above a delisting threshold.

The companies that did not survive the dot-com crash mostly died because they ran out of money before they were willing to do those things. The willingness to do the ugly, unglamorous, undignified things is not something luck provides. It is something a leader either has or doesn’t, and David Moore had it in abundance when the circumstances required it most.

The Thread That Never Changed

Through four decades that ran from Turner Broadcasting in 1979 to the WPP acquisition in 2007 and beyond, one operational principle stayed constant in every environment and under every form of pressure. As long as there was someone left to call, they were not done.

That principle sustained a company through one of the most dramatic and prolonged financial collapses in internet history. It produced a $649 million outcome from a company that had traded at nine cents a share. It built a digital advertising industry from a category that barely existed in 1997. And it generated a book that tells the full story, including the parts that don’t photograph well, don’t fit on a slide, and don’t appear in the version of the story that most people tell themselves about how successful companies are built.

Dave Morgan called David the Winston Churchill of dot-com CEOs. The comparison is generous. What David would say about himself is simpler: he was the last person in the room still willing to pick up the phone. That turned out to be enough.

The story of the man who was still making sales calls when everyone else had declared the game over. The 24/7 CEO by David Moore is available now on Amazon.

Inflation Has Nearly Erased Recent Pay Raises for U.S. Workers

Inflation and pay raises moved at different speeds for U.S. workers in September 2026. Federal data show average hourly earnings rose 3.0% over the year while consumer prices climbed 3.7%, leaving inflation-adjusted pay 0.7% lower. The figures explain why bigger paychecks did not necessarily mean greater purchasing power.

Key Takeaways

  • U.S. real average hourly earnings declined 0.7% over the 12 months through September 2026, according to the Bureau of Labor Statistics.
  • Consumer prices increased 3.7% annually, while nominal average hourly earnings grew 3.0%.
  • Gasoline prices jumped 9.1% in September and 34.2% from a year earlier.
  • Real average weekly earnings fell 0.5% in September, while producer prices rose 1.3%.

In September, U.S. workers’ average hourly pay rose more slowly than prices. The Bureau of Labor Statistics reported on October 14 that earnings increased 0.1% from August, compared with a 0.6% rise in the Consumer Price Index. Real hourly earnings, which account for changes in consumer prices, fell 0.5% for the month.

Over 12 months, the difference was smaller but persistent: hourly pay increased 3.0%, consumer prices climbed 3.7%, and real hourly earnings fell 0.7%. The findings cover private nonfarm payroll employees.

Inflation and Pay Raises Left Real Hourly Earnings Down 0.7%

Monthly figures show how raises lose value. The average hourly rate for private-sector workers reached $37.81 in September, up from $37.76 in August and $36.70 a year earlier. The higher dollar figure does not account for the price increases recorded over the same period.

The Consumer Price Index measures changes in the cost of a range of goods and services. The earnings adjustment uses that price measure to show how much average hourly pay can purchase. A decrease in real earnings means average wage growth did not match the overall rise in consumer prices.

September’s decline also followed a weaker August reading. Real average hourly earnings fell 0.1% from July to August, before the 0.5% September drop. On a year-over-year basis, real hourly earnings had declined 0.3% in August, compared with 0.7% in September.

These averages include changes in the mix of jobs and industries. They do not establish that all workers received a raise or that every household faced the national inflation rate.

Gasoline Prices Jumped 9.1% as Household Costs Increased

Gasoline was the clearest reason for September’s faster price growth. Its consumer price index surged 9.1% from August and 34.2% from September 2025. The Bureau of Labor Statistics said gasoline accounted for more than half of the month’s 0.6% rise in the overall consumer price index.

Other energy expenses increased at a slower annual pace. Electricity prices rose 4.4% from a year earlier, and natural gas service increased 5.0%. The energy index overall rose 5.2% for September and 20.4% over 12 months.

Energy prices outpaced wages in an earlier 2026 comparison, adding context to the latest gasoline increase. The impact on a household depends on how much it drives, the type of home it occupies and local utility costs.

Food moved differently. Grocery prices declined 0.1% in September and were up 1.8% over 12 months. Prices for food consumed away from home increased 0.2% during the month and 3.5% over the year, according to the same report.

Shelter costs rose 0.4% in September and 3.2% over the year. Prices excluding food and energy increased 0.3% for the month and 2.6% over 12 months. The latter measure indicates that price increases extended beyond the energy category, even though gasoline was the largest contributor to September’s monthly rise.

Longer Workweeks Failed to Prevent Lower Real Weekly Earnings

The difference between hourly and weekly earnings matters when assessing pay. Average weekly earnings reflect both the rate of pay and the hours worked. A longer workweek can raise total pay even if purchasing power per hour declines.

Average private-sector weekly hours stood at 34.4 in September, unchanged from August but higher than the 34.2 hours recorded a year earlier. Over the 12-month period, average hours increased 0.6%, helping lift nominal weekly earnings by 3.6%.

Once adjusted for inflation, however, real average weekly earnings fell 0.1% from September 2025. The monthly decline was sharper at 0.5%, consistent with the drop in inflation-adjusted hourly earnings while the average workweek stayed unchanged.

Production and nonsupervisory employees experienced a similar annual outcome. Their nominal average hourly earnings increased 3.3% over 12 months, but real hourly earnings fell 0.6% under the price index used for that group. Real weekly earnings declined 0.3% over the year.

The figures are national averages rather than changes in take-home pay. Taxes, payroll deductions, benefits and household income from other sources are outside the hourly earnings comparison. The data also do not identify whether changes in working hours were voluntary.

Business Costs Increased as Consumer Sentiment Declined

Cost pressure appeared in measures of business prices as well. The Producer Price Index for final demand rose 1.3% in September, its largest monthly advance since March 2022. Producer prices were 6.3% above their level a year earlier, the Bureau of Labor Statistics reported October 15.

Prices for final-demand goods increased 2.6% during the month, while prices for services rose 0.8%. Transportation and warehousing services climbed 3.4%. Producer prices are not retail prices, and a change at the business level does not necessarily produce an equal increase at checkout.

The figures followed higher services input costs reported in the Institute for Supply Management’s September survey. Its prices index rose to 74.0 from 72.6 in August. That reading indicates more widespread price increases among surveyed businesses, not a 74% jump in costs.

Consumer attitudes weakened alongside the price reports. The University of Michigan’s preliminary October consumer sentiment index declined to 46.3 from 48.1 in September. Its current conditions gauge fell to 44.7 from 50.9, while expectations for inflation over the next year rose to 4.7% from 4.6%.

Joanne Hsu, director of the university’s Surveys of Consumers, wrote that “Frustration over cost-of-living continues to mount” in commentary accompanying the October results. The survey describes consumer perceptions, while federal wage and price reports measure changes in average earnings and inflation.

The September comparison between inflation and pay raises showed a 0.7% annual decline in real average hourly earnings. The preliminary October survey separately recorded consumer sentiment at 46.3, providing a measure of household perceptions alongside the federal earnings data.

Frequently Asked Questions

Why did inflation and pay raises leave workers with less purchasing power?

Inflation and pay raises increased at different rates during the year through September 2026. Consumer prices rose 3.7%, compared with 3.0% growth in nominal average hourly earnings, resulting in a 0.7% decline in inflation-adjusted hourly earnings.

How much did real hourly earnings fall in September 2026?

Real average hourly earnings declined 0.5% from August to September 2026, according to the Bureau of Labor Statistics. The annual decrease reached 0.7% compared with September 2025.

Which expenses contributed most to September’s inflation increase?

Gasoline prices rose 9.1% during September, accounting for more than half of the monthly increase in the Consumer Price Index. Shelter prices also increased, while grocery prices declined slightly during the month.

Did longer working hours offset the decline in purchasing power?

Average weekly working hours increased 0.6% over the year through September 2026. However, real average weekly earnings still declined 0.1% over the same period.

What did the October 2026 consumer sentiment report show?

The University of Michigan’s preliminary October consumer sentiment index fell to 46.3 from 48.1 in September. Expectations for inflation over the following year increased to 4.7% from 4.6%.

Working Capital Advances Explained: Costs, Terms and Smart Choices

A working capital advance can put working capital in a business account within a day or two, often without the credit score or paperwork a bank demands. That speed makes it one of the most popular forms of alternative business financing. It also makes it one of the most misunderstood. Owners who sign without understanding the true cost, or who stack one advance on another, can find their cash flow squeezed for months.

This article explains how a working capital advance works, what it really costs, the contract terms that matter, and how to choose a funder you can trust.

What a working capital advance actually is

A working capital advance is not a loan. It is the purchase of a business’s future receivables at a discount. The funder pays a lump sum today, and the business agrees to deliver a fixed amount of its future sales, called the purchased amount or payback, until that amount is fully remitted.

Because it is a sale rather than a loan, a working capital advance is priced with a factor rate instead of an interest rate, and the contract usually includes a reconciliation right. That right lets the business ask for its payments to be adjusted if revenue falls. Most advances today are repaid by fixed daily or weekly ACH debits from the business bank account.

The typical process looks like this:

  1. Application. A short form and three to six months of business bank statements.
  2. Underwriting. The funder reviews monthly revenue, deposit frequency, average daily balance, negative days, existing advances and industry. Credit matters, but it rarely decides the deal alone.
  3. Offer. An amount, a factor rate, a payment and an estimated term.
  4. Contract and verification. The owner signs, and the funder confirms identity and bank access.
  5. Funding. Money arrives by wire or ACH, often within 24 to 72 hours. Any fees are deducted from this amount.
  6. Remittance. Debits begin and continue until the purchased amount is delivered.

The terms you need to know

Factor rate. The multiplier that sets the payback. A factor rate of 1.30 on $40,000 means $52,000 is owed.

Holdback. The share of receivables the funder is entitled to. Fixed debits are meant to approximate it.

Term. The estimated time to remit the payback, often four to eighteen months.

Position. Each open advance is a position. A second advance taken while the first is open is a second position.

Stacking. Taking further advances while others are still open.

Points. The commission the funder pays the broker, expressed as a percentage of the funded amount.

UCC filing. A public lien the funder records on business assets. Ask when it will be released after payoff.

What an advance really costs

Factor rates look small, which is why they are easy to underestimate. Consider a restaurant with $90,000 in monthly deposits that accepts a $60,000 advance at a factor rate of 1.38. The total payback is $82,800, so the cost of funds is $22,800. Over an estimated nine months, about 189 business days, the daily debit is roughly $438.

That 38% cost is not a 38% annual rate. Because the balance is paid down every day, the business has the full $60,000 for only a moment. Expressed as an annual percentage rate, a deal like this works out close to 100%, and a shorter term at the same factor rate pushes it higher still.

None of this makes the advance a bad decision. If the money replaces a broken walk-in cooler that would otherwise close the kitchen, or buys inventory at a deep discount, the return can outweigh the cost. The goal is to decide with the real numbers in front of you. Always ask for four figures in writing: the net amount you will receive, the total payback, the payment amount and frequency, and the expected term.

Watch for fees as well. A legitimate origination or underwriting fee should be stated in the contract and deducted from the funded amount. Be wary of monthly administrative charges added on top of the agreed debit, and of large processing fees charged by a broker who is already being paid points by the funder.

Positions, stacking and the debt trap

Most owners take a first advance for a good reason. Trouble usually starts when a second and third follow before the first is paid down. Each new position adds its own debit. A business remitting $438 a day on one advance can find itself remitting $1,200 a day across three, from the same revenue. Some first-position contracts also prohibit further financing, so stacking can put the business in breach.

If you are already carrying several positions, consider the alternatives before adding another: a consolidation into one longer advance, a reverse consolidation that lowers the daily payment, a reconciliation request to existing funders, or advice from a business attorney.

Reading the contract

Working capital agreements are long and written in the funder’s favor. Before signing, check that the purchased amount and payment match the offer you were quoted. Find the reconciliation clause and note how to request an adjustment if sales drop. List every fee and when it is charged. Understand the personal guarantee, which usually covers the owner’s performance under the contract, and the events that count as default. Look for anti-stacking language that restricts future financing, and confirm whether paying early earns a discount or whether the full purchased amount is owed regardless.

Above all, remember that verbal promises do not count. “Take this now and we will lower your rate in three months” means nothing unless it is written into the agreement.

Who a working capital advance suits

An advance tends to fit businesses with steady card or bank deposits, a short-term need with a clear return, and limited access to cheaper credit. Restaurants, retailers, salons, auto repair shops, contractors and e-commerce sellers use them regularly. It tends not to fit businesses with falling revenue, thin margins that cannot absorb a daily debit, or long-term needs such as buying property.

Choosing the right funder

Funders differ sharply. Some fund only first positions above a revenue floor. Others specialize in particular industries or consider past defaults. Sending a file to the wrong funder wastes time, triggers extra credit inquiries and spreads your bank statements around.

MCA Directory was built to solve that problem. Brokers search funders by monthly revenue, credit score, open positions, product type and industry, and see each funder’s minimum revenue, credit floor, position limits, default policy, maximum term, maximum funding and excluded states and industries. Verified funders are hand-vetted and confirmed to be actively funding. The platform is free for brokers, so owners benefit most when the broker they hire uses it. Ask your broker how they choose funders and which funders will receive your file.

Owners can also check reputation directly. On MCA Directory, brokers review funders on funding speed, underwriting honesty and merchant treatment, and every review requires a company email and supporting documents. For proof that a funder or broker actually closes deals, the FundedUSA Instagram page posts confirmations of businesses funded through reliable lenders and brokers.

How funders and brokers join the platform

Funders that want brokers to find them can apply through the verified funder listing page, which sets out the listing criteria, placement options and the vetting behind the verified badge. Brokers can set up access through the broker marketplace, where CRMs, lead providers, legal services and other tools are organized by category.

Spotting a fake working capital offer

Working capital scams depend on owners not knowing what a normal offer looks like. Published funder criteria fix that. If a company offers a business doing $20,000 a month a $500,000 advance over two years at a tiny factor rate, real market terms show how far outside reality that offer sits. Scammers lead with irresistible terms precisely because they never intend to fund.

The most important protection is a single rule: no legitimate working capital provider requires you to send money before you have a signed agreement and the funds are in your account. A request for a security deposit, insurance premium, escrow payment or release fee, especially by wire, Zelle, crypto or cashier’s check, is the signal to stop.

MCA Directory reinforces that rule with a public guide to the advance-fee scam, red flags for every side of a deal, and a private fraud reporting form. If you have already paid, call your bank immediately about a recall, report it to the FTC and the FBI’s IC3, keep every record, and file a private report.

The bottom line

A working capital advance is a tool, not a lifeline. Used for a short-term need with a clear return, from a funder that fits your profile, it can move a business forward. Know your numbers, read the contract, never pay a fee before funding, and verify every company before you share your statements.

Disclaimer: This article is for general information only and is not legal, tax or financial advice. Working capital costs, terms and eligibility vary by funder and by business. Review any agreement carefully and consult a qualified professional before signing.

Why Waiting for Lower Mortgage Rates Can Cost Buyers More

Many would-be buyers are sitting out the market, waiting for mortgage rates to fall. One industry veteran argues that waiting often costs more than it saves.

The Rates Buyers Remember Are Not Coming Back Soon

With the 30-year fixed rate climbing above 7.5 percent in 2026, buyers who remember pandemic-era rates below 3 percent have been reluctant to commit. Bill Gaul, CEO of Builders Update and chair of the RESO Data Dictionary New Construction Subcommittee, thinks that wait could be a long one. He expects rates to stay elevated and believes a figure closer to 8 percent could become the norm for years to come. “The days of 3 percent are long gone,” Gaul says.

The Math of Waiting

The problem with waiting, Gaul argues, is that the savings from a slightly lower rate can be erased by a higher purchase price. As buyers return to the market when rates ease, renewed competition tends to push prices up.

By his estimate, someone who waits can watch the same home rise by thousands of dollars, offsetting the benefit of the lower rate. A buyer ends up paying one way or another, he says, just on a different line of the contract.

Buy What You Need, Not What You Want

Gaul’s guidance is to focus on affordability rather than timing. He encourages buyers to separate what they need from what they want, and to buy a home they can comfortably afford today rather than stretching on the assumption that they will refinance later. “Buy the house you can afford, live in it, and enjoy it,” he says.

He also urges caution on incentives. A builder’s rate buydown can make a monthly payment look manageable, but many buydowns are temporary and still require the buyer to qualify at the full rate, so a cost that feels comfortable at first can rise later. Reading those terms closely, Gaul says, is part of buying within your means rather than beyond them.

None of this is a prediction that rates will never fall. It is an argument that timing the market is harder, and often costlier, than buying what you can afford when you are ready. For buyers weighing whether to wait, Gaul’s message is that the cost of sitting out is easy to underestimate.

About the Expert: Bill Gaul is CEO of Builders Update and chair of the RESO Data Dictionary New Construction Subcommittee. Based in Austin, Texas, he specializes in new construction data and MLS interoperability.

About Builders Update: Builders Update is one of North America’s leading providers of new construction inventory data, serving builders, MLSs, brokers, and real estate professionals. Through its platform and commitment to data quality, Builders Update advances transparency, interoperability, and collaboration within the new construction sector. For more information, visit www.buildersupdate.com.

Disclaimer: This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.